Our bi-weekly Opinion provides you with latest updates and analysis on major capital market and financial investment industry issues.

The Impact Investment Market in Korea: Current Status and Challenges
Publication date Aug. 11, 2026
Summary
Impact investing is an investment approach that seeks to generate positive, measurable social value alongside financial return. Its core elements are intentionality in the pursuit of social value, the simultaneous pursuit of financial return and social value, and the measurement and disclosure of the outcomes investment activities produce.
The global impact investment market has grown rapidly, with assets under management (AUM) rising from roughly USD 60 billion in 2014 to USD 418 billion in 2024 — an average annual growth rate of about 20%. Investment targets have diversified as well, moving beyond an initial concentration in financial services into sectors such as energy and healthcare. Korea’s market has expanded on a similar trajectory, from seven funds with KRW 100 billion in AUM in 2004 to 301 funds with KRW 6.65 trillion in 2024, and now constitutes a meaningful segment of the venture capital fund market. Although Korean impact funds generally set hurdle rates more than a percentage point below those of conventional venture capital funds, the realized performance of liquidated funds shows no significant difference between the two. Impact investing, on this evidence, is not “an investment that sacrifices return” but “an investment with a different expected-return structure.”
The market has now outgrown its early ecosystem-building stage and needs a framework capable of supporting scale-up. That will mean addressing several challenges at once: demonstrating that reasonable returns are attainable, standardizing the measurement and reporting of social impact, identifying and cultivating impact startups, expanding the role of limited partners (LPs), making effective use of policy funds, strengthening tax incentives for impact investors, and establishing a legal definition of impact enterprises.
The global impact investment market has grown rapidly, with assets under management (AUM) rising from roughly USD 60 billion in 2014 to USD 418 billion in 2024 — an average annual growth rate of about 20%. Investment targets have diversified as well, moving beyond an initial concentration in financial services into sectors such as energy and healthcare. Korea’s market has expanded on a similar trajectory, from seven funds with KRW 100 billion in AUM in 2004 to 301 funds with KRW 6.65 trillion in 2024, and now constitutes a meaningful segment of the venture capital fund market. Although Korean impact funds generally set hurdle rates more than a percentage point below those of conventional venture capital funds, the realized performance of liquidated funds shows no significant difference between the two. Impact investing, on this evidence, is not “an investment that sacrifices return” but “an investment with a different expected-return structure.”
The market has now outgrown its early ecosystem-building stage and needs a framework capable of supporting scale-up. That will mean addressing several challenges at once: demonstrating that reasonable returns are attainable, standardizing the measurement and reporting of social impact, identifying and cultivating impact startups, expanding the role of limited partners (LPs), making effective use of policy funds, strengthening tax incentives for impact investors, and establishing a legal definition of impact enterprises.
Impact Investment
Interest in impact investment is growing as a financial instrument that seeks to solve social problems taking advantage of market mechanisms. Although it has a relatively short history and no universally accepted definition, impact investment can be defined as “investment activity that seeks to generate positive and measurable social impact in addition to financial returns.” More specifically, it can be understood in terms of the following three dimensions.
The first criterion is intentionality: the aim to generate positive social value must be explicitly embedded in every stage of the investment decision-making process. Positive outcomes that arise only incidentally, as an unintended by-product of an investment, therefore do not qualify as impact investing. Yet because it is difficult to specify in advance which outcomes count as social value, a workable standard is to recognize an investment as impact investing once it clearly states the social value it aims to create and succeeds in attracting capital on that basis.
Second, whereas conventional investment pursues financial return alone, impact investing pursues both financial return and social value – double-bottom line. The two objectives are not necessarily in tension, rather, the differing weights investors assign to each give rise to an ecosystem of varied preferences and objectives.
Third, impact investing measures and actively manages not only the financial returns an investment generates but also the social value it creates, and it discloses the results transparently to external stakeholders. This gives investors and other stakeholders an objective basis for verifying whether the commitment to creating social value through investment activity has actually been fulfilled. The modern concept of impact investing was first put forward in 2007 at an international convening hosted by the Rockefeller Foundation in Bellagio, Italy. It has evolved steadily since then, and by the mid-2010s it had consolidated around the three elements discussed above.
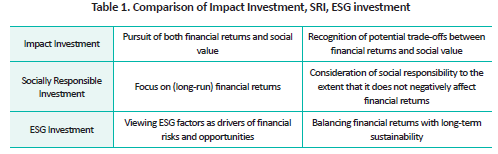
Impact investing is often used interchangeably with related concepts such as socially responsible investment (SRI) and ESG investing, yet meaningful distinctions exist. SRI may be defined as “an approach to investment decision-making in which particular non-financial factors are organically integrated into the analysis and taken into account.” On this definition, impact investing can be regarded as a subset of SRI. The two nonetheless diverge sharply in how they handle potential conflicts between financial return and social value.
SRI emphasizes that pursuing social value need not come at the cost of financial return and may in fact strengthen long-term performance by improving sustainability. Impact investing, by contrast, does not deny that the two can conflict; it holds instead that opting for greater social value, even at the expense of some financial value, may be fully consistent with investors’ preferences. In addition, whereas impact investing treats the measurement, management, and reporting of social value as core components of the investment process, SRI is comparatively less proactive on this front.
Impact investing also shares substantial common ground with ESG investing: both attend to environmental (E) and social (S) factors and both stress measurement and management. At the practical level, however, they part ways. ESG is primarily a tool for assessing how well companies manage sustainability-related risks and opportunities, and it relies largely on backward-looking indicators; impact investing, by contrast, is a strategy built on forward-looking indicators of the outcomes an investment sets out to achieve. ESG investing also stops short of explicitly acknowledging trade-offs with financial return, calling instead for negative externalities to be minimized or offset, whereas impact investing accepts that such trade-offs may arise and actively pursues positive externalities. One consequence is that ESG investors, to discharge their fiduciary duties, must show that taking ESG factors into account does not harm financial return, while in impact investing the standard applied in judging whether fiduciary duties have been met is comparatively more permissive.
Like conventional financial markets, the impact investment market is made up of capital suppliers, capital demanders, intermediaries that link the two sides, and infrastructure institutions that support the smooth functioning of the market. Capital suppliers include individual investors, conventional institutional investors such as pension funds, insurance companies, corporations, and sovereign wealth funds, and nonprofit and public-sector entities such as foundations, charitable organizations, and development finance institutions (DFIs). Among individuals, high-net-worth investors supply capital through family offices and similar vehicles tend to figure more prominently than small retail investors. Conventional institutional investors—the largest source of capital in the impact investing market, led by pension funds—place heavy emphasis on financial return. To discharge their fiduciary duties, they commit capital on the premise that doing so will not impair financial returns, at least over the long run. Nonprofit and public-sector entities such as foundations and DFIs, by contrast, are by their nature inclined to take social value creation more seriously. Capital demanders are also diverse — impact enterprises, social enterprises, social ventures, and social projects —but all share the objective of pursuing social value and financial return together.
There are, as in the conventional market markets, two important frictions in the impact investment market that can impede the efficient working of market mechanisms, transaction costs and information asymmetry. Financial intermediaries such as impact banks and impact investment funds play an important role in overcoming these difficulties. In continental Europe, where the tradition of universal banking along with cooporative banking runs deep, a considerable number of banks, commercial and cooperative, participate in the impact investment market as capital suppliers. In a market marked by high credit risk and a lack of collateral on the part of borrowers, however, it is difficult in practice for banks subject to stringent capital regulation to take a leading role. Impact investment funds therefore emerge as the most important intermediaries. These funds set their investment objectives in advance, raise capital, and supply equity or debt financing to impact enterprises and social projects. They operate mainly in private markets, though they have recently begun to extend into public markets as well.
Trends in Global and Korean Impact Investment Markets
The global impact investing market is growing rapidly. The Global Impact Investing Network (GIIN) surveys impact investors worldwide and publishes data on investment scale, instruments, target returns, sectors, and impact measurement and management. Impact investment assets under management (AUM) rose from roughly USD 60 billion in 2014 to USD 239 billion in 2018 and USD 418 billion in 2024 — an average annual growth rate of about 20%. As of 2025, the sectors drawing the most impact capital are financial services (21%), energy (20%), healthcare (11%), and agriculture and forestry (11%). Investment targets are diversifying beyond the long-standing concentration in financial services, including microfinance, and housing, extending into energy, healthcare services, manufacturing, and information and communications technology. Energy in particular is attracting capital at a rapid pace as vehicles such as green bonds and ESG funds proliferate.
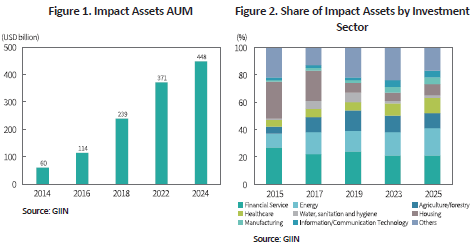
By investment vehicle, private assets made up the bulk of allocations in 2024, with private equity at 41% and private debt at 21%. Public assets held a meaningful share as well: public equity at 12% and public debt at 9%. Allocations to public assets have grown in recent years, alongside a shift from debt toward equity. This pattern is closely tied to the broader expansion of ESG-related investment in public markets. On financial return expectations, the share of respondents targeting risk-adjusted, market-rate returns climbed steadily from the mid-50% range in the mid-2010s to roughly 90% in 2025, evidence that investors who approach impact assets on commercial terms now constitute the dominant group. The share willing to accept below-market returns in exchange for social value, meanwhile, declined gradually — from 23% in 2014 to 18% in 2020 and 15% in 2024.
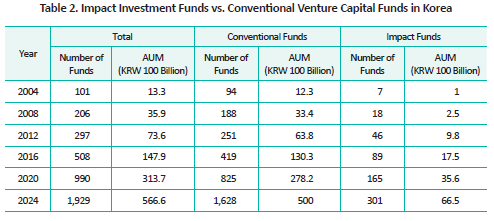
Data from the Venture Investment Disclosure System (DIVA), maintained by the Comprehensive Venture Investment Portal, show that Korea's impact investing market has expanded rapidly. In 2004, seven impact funds managed KRW 100 billion in assets. The figures climbed to 46 funds and KRW 980 billion in 2012, and to 301 funds and KRW 6.65 trillion in 2024. As of 2024, impact funds made up 16% of all venture funds by number and 12% by assets under management, having established themselves as a meaningful pillar of the venture fund market. Their hurdle rates were set more than a full percentage point below those of conventional funds that do not pursue impact, confirming a willingness among impact funds to accept some sacrifice in financial return for the sake of social value. Yet a comparison of realized performance among funds that had completed their investment periods and been liquidated revealed no significant difference between impact funds and conventional ones. Impact investing, on this evidence, is not “investing at the expense of return” but “investing on a different expected-return structure”: the pursuit of social value shapes target returns and investment strategy without necessarily translating into a gap in realized financial performance.
Challenges and Tasks
Impact investment still accounts for only a very small share of the alternative investment market. For it to enter a phase of full-fledged growth, capital must flow in from conventional financial markets — and that in turn requires demonstrating, through actual cases, that impact investing can deliver satisfactory returns at market rates. A rise in successful exits via IPO or acquisition, along with the emergence of impact unicorns, would be particularly persuasive, giving investors a track record to point to. Converting latent demand for social outcomes into actual investment calls for further steps: social performance indicators should be built explicitly into investment evaluation metrics, the measurement and reporting of social outcomes should be standardized, and asset manager compensation should be tied to the outcomes achieved. These measures bear directly on preventing impact washing and securing the market's credibility.
Next, systematic programs and stage-by-stage growth pathways are needed to identify and cultivate economically sustainable impact companies — startups in particular — that create social value. Policy funding and public-private blended financing for accelerators focused on social impact should be expanded, and effective early-stage consulting should help lay a foundation for growth. Accelerators should work closely with portfolio companies from the outset on core challenges such as business planning, KPI setting, and market entry. Most important is developing accelerators with the capacity to connect portfolio companies to a broad range of investors at the scale-up stage.
Expanding fund commitments, above all through an active role for limited partners (LPs), matters equally for broadening the impact investment ecosystem. Because the social outcomes impact investing generates are positive externalities, they are liable to be undersupplied. There is thus a strong case for the government and public sector to help create the market by establishing policy funds as seed capital. Public funds such as Korea Venture Investment Corp. and Korea Growth Investment Corp. already act as LPs, but larger allocations merit consideration. Venture funds, currently confined to equity investment, might also be permitted within defined limits to extend alternative forms of financing such as loans or bond purchases; alternatively, specialized impact investment institutions could be introduced. Mechanisms should at the same time be put in place to preserve clear standards and objectives for impact investing without unduly narrowing eligible sectors or targets, and the information-sharing and capacity-building networks that ease the entry of new investment actors should be reinforced.
Because policy funding by the government alone will not suffice, collaboration with private capital through arrangements such as blended finance is essential. Expanded tax incentives deserve consideration as a means of drawing in high-net-worth individuals; given the positive externalities that social value generates, benefits more generous than those available for purely financial venture investment would be defensible. Any such measure would require clear legal definitions of impact companies and impact funds. One approach would be a certification system modeled on venture company certification; others would link eligibility to B Corp certification or adapt the Public Benefit Corporation (PBC) framework, of the kind Delaware introduced in the United States, to Korean conditions. Public-interest corporations warrant attention as well: they held roughly KRW 350 trillion in assets as of 2023 yet directed only about 2% to impact investments. Constraints including the 5% ceiling on shareholdings and the requirement that income be applied to designated public-interest purposes discourage them from participating actively. These rules should be relaxed to the extent that doing so does not compromise the goal of preventing concentrated economic power. Should the pending amendments to the Inheritance Tax and Gift Tax Act pass, public-interest corporations could emerge as significant providers of capital. Reflecting corporate impact investments in ESG assessments, or extending tax benefits tied to carbon-emission reductions, would also be worth exploring.
Impact idnetities, for their part, must become self-sufficient as for-profit enterprises. The appropriate aim is therefore not extensive dedicated support but assurance that they are not shut out of general support policies for small and medium-sized enterprises. Ecosystem infrastructure, however, does require public backing: dedicated organizations to support the production and dissemination of impact market information and to inform policy development, government support for standardized impact measurement tools and databases, and shared evaluation criteria built on a long-term perspective.
Conclusion
Korea’s impact investment market is moving beyond early stage of laying the foundation of eco-system and develop new framework capable of supporting scale-up of the industry.
Full-fledged growth, however, will require overcoming structural obstacles: an insufficient supply of capital, the absence of standardized social performance measurement, uncertainty around exits, and too few impact startups. Beneath these lie two more basic conditions — market foundations for the double bottom line model, which pursues financial return and social value together, that remain fragile, and an exit horizon longer than that of conventional venture capital.
Meeting these challenges will take work on three fronts. On the capital side, the pool of impact LPs needs to be enlarged and diversified, policy funds scaled up, tax incentives introduced, and long-term capital drawn from pension funds and insurance companies; public-private blended finance should be expanded and funding instruments diversified. On the exit side, secondary and public-market channels need strengthening. On the measurement side, social value measurement must be made objective and transparent, within a multi-layered system able to accommodate more than one definition of impact and more than one method of gauging it. Government policy support is critical throughout.
Financial return and social outcomes are not inherently at odds, and evidence is accumulating that the two can coexist where investment structures are designed with care. The task ahead is no longer to lay the groundwork for an impact investing ecosystem but to design a framework capable of carrying it through scale-up.
Interest in impact investment is growing as a financial instrument that seeks to solve social problems taking advantage of market mechanisms. Although it has a relatively short history and no universally accepted definition, impact investment can be defined as “investment activity that seeks to generate positive and measurable social impact in addition to financial returns.” More specifically, it can be understood in terms of the following three dimensions.
The first criterion is intentionality: the aim to generate positive social value must be explicitly embedded in every stage of the investment decision-making process. Positive outcomes that arise only incidentally, as an unintended by-product of an investment, therefore do not qualify as impact investing. Yet because it is difficult to specify in advance which outcomes count as social value, a workable standard is to recognize an investment as impact investing once it clearly states the social value it aims to create and succeeds in attracting capital on that basis.
Second, whereas conventional investment pursues financial return alone, impact investing pursues both financial return and social value – double-bottom line. The two objectives are not necessarily in tension, rather, the differing weights investors assign to each give rise to an ecosystem of varied preferences and objectives.
Third, impact investing measures and actively manages not only the financial returns an investment generates but also the social value it creates, and it discloses the results transparently to external stakeholders. This gives investors and other stakeholders an objective basis for verifying whether the commitment to creating social value through investment activity has actually been fulfilled. The modern concept of impact investing was first put forward in 2007 at an international convening hosted by the Rockefeller Foundation in Bellagio, Italy. It has evolved steadily since then, and by the mid-2010s it had consolidated around the three elements discussed above.
Impact investing is often used interchangeably with related concepts such as socially responsible investment (SRI) and ESG investing, yet meaningful distinctions exist. SRI may be defined as “an approach to investment decision-making in which particular non-financial factors are organically integrated into the analysis and taken into account.” On this definition, impact investing can be regarded as a subset of SRI. The two nonetheless diverge sharply in how they handle potential conflicts between financial return and social value.
SRI emphasizes that pursuing social value need not come at the cost of financial return and may in fact strengthen long-term performance by improving sustainability. Impact investing, by contrast, does not deny that the two can conflict; it holds instead that opting for greater social value, even at the expense of some financial value, may be fully consistent with investors’ preferences. In addition, whereas impact investing treats the measurement, management, and reporting of social value as core components of the investment process, SRI is comparatively less proactive on this front.
Impact investing also shares substantial common ground with ESG investing: both attend to environmental (E) and social (S) factors and both stress measurement and management. At the practical level, however, they part ways. ESG is primarily a tool for assessing how well companies manage sustainability-related risks and opportunities, and it relies largely on backward-looking indicators; impact investing, by contrast, is a strategy built on forward-looking indicators of the outcomes an investment sets out to achieve. ESG investing also stops short of explicitly acknowledging trade-offs with financial return, calling instead for negative externalities to be minimized or offset, whereas impact investing accepts that such trade-offs may arise and actively pursues positive externalities. One consequence is that ESG investors, to discharge their fiduciary duties, must show that taking ESG factors into account does not harm financial return, while in impact investing the standard applied in judging whether fiduciary duties have been met is comparatively more permissive.
There are, as in the conventional market markets, two important frictions in the impact investment market that can impede the efficient working of market mechanisms, transaction costs and information asymmetry. Financial intermediaries such as impact banks and impact investment funds play an important role in overcoming these difficulties. In continental Europe, where the tradition of universal banking along with cooporative banking runs deep, a considerable number of banks, commercial and cooperative, participate in the impact investment market as capital suppliers. In a market marked by high credit risk and a lack of collateral on the part of borrowers, however, it is difficult in practice for banks subject to stringent capital regulation to take a leading role. Impact investment funds therefore emerge as the most important intermediaries. These funds set their investment objectives in advance, raise capital, and supply equity or debt financing to impact enterprises and social projects. They operate mainly in private markets, though they have recently begun to extend into public markets as well.
Trends in Global and Korean Impact Investment Markets
The global impact investing market is growing rapidly. The Global Impact Investing Network (GIIN) surveys impact investors worldwide and publishes data on investment scale, instruments, target returns, sectors, and impact measurement and management. Impact investment assets under management (AUM) rose from roughly USD 60 billion in 2014 to USD 239 billion in 2018 and USD 418 billion in 2024 — an average annual growth rate of about 20%. As of 2025, the sectors drawing the most impact capital are financial services (21%), energy (20%), healthcare (11%), and agriculture and forestry (11%). Investment targets are diversifying beyond the long-standing concentration in financial services, including microfinance, and housing, extending into energy, healthcare services, manufacturing, and information and communications technology. Energy in particular is attracting capital at a rapid pace as vehicles such as green bonds and ESG funds proliferate.
Data from the Venture Investment Disclosure System (DIVA), maintained by the Comprehensive Venture Investment Portal, show that Korea's impact investing market has expanded rapidly. In 2004, seven impact funds managed KRW 100 billion in assets. The figures climbed to 46 funds and KRW 980 billion in 2012, and to 301 funds and KRW 6.65 trillion in 2024. As of 2024, impact funds made up 16% of all venture funds by number and 12% by assets under management, having established themselves as a meaningful pillar of the venture fund market. Their hurdle rates were set more than a full percentage point below those of conventional funds that do not pursue impact, confirming a willingness among impact funds to accept some sacrifice in financial return for the sake of social value. Yet a comparison of realized performance among funds that had completed their investment periods and been liquidated revealed no significant difference between impact funds and conventional ones. Impact investing, on this evidence, is not “investing at the expense of return” but “investing on a different expected-return structure”: the pursuit of social value shapes target returns and investment strategy without necessarily translating into a gap in realized financial performance.
Impact investment still accounts for only a very small share of the alternative investment market. For it to enter a phase of full-fledged growth, capital must flow in from conventional financial markets — and that in turn requires demonstrating, through actual cases, that impact investing can deliver satisfactory returns at market rates. A rise in successful exits via IPO or acquisition, along with the emergence of impact unicorns, would be particularly persuasive, giving investors a track record to point to. Converting latent demand for social outcomes into actual investment calls for further steps: social performance indicators should be built explicitly into investment evaluation metrics, the measurement and reporting of social outcomes should be standardized, and asset manager compensation should be tied to the outcomes achieved. These measures bear directly on preventing impact washing and securing the market's credibility.
Next, systematic programs and stage-by-stage growth pathways are needed to identify and cultivate economically sustainable impact companies — startups in particular — that create social value. Policy funding and public-private blended financing for accelerators focused on social impact should be expanded, and effective early-stage consulting should help lay a foundation for growth. Accelerators should work closely with portfolio companies from the outset on core challenges such as business planning, KPI setting, and market entry. Most important is developing accelerators with the capacity to connect portfolio companies to a broad range of investors at the scale-up stage.
Expanding fund commitments, above all through an active role for limited partners (LPs), matters equally for broadening the impact investment ecosystem. Because the social outcomes impact investing generates are positive externalities, they are liable to be undersupplied. There is thus a strong case for the government and public sector to help create the market by establishing policy funds as seed capital. Public funds such as Korea Venture Investment Corp. and Korea Growth Investment Corp. already act as LPs, but larger allocations merit consideration. Venture funds, currently confined to equity investment, might also be permitted within defined limits to extend alternative forms of financing such as loans or bond purchases; alternatively, specialized impact investment institutions could be introduced. Mechanisms should at the same time be put in place to preserve clear standards and objectives for impact investing without unduly narrowing eligible sectors or targets, and the information-sharing and capacity-building networks that ease the entry of new investment actors should be reinforced.
Because policy funding by the government alone will not suffice, collaboration with private capital through arrangements such as blended finance is essential. Expanded tax incentives deserve consideration as a means of drawing in high-net-worth individuals; given the positive externalities that social value generates, benefits more generous than those available for purely financial venture investment would be defensible. Any such measure would require clear legal definitions of impact companies and impact funds. One approach would be a certification system modeled on venture company certification; others would link eligibility to B Corp certification or adapt the Public Benefit Corporation (PBC) framework, of the kind Delaware introduced in the United States, to Korean conditions. Public-interest corporations warrant attention as well: they held roughly KRW 350 trillion in assets as of 2023 yet directed only about 2% to impact investments. Constraints including the 5% ceiling on shareholdings and the requirement that income be applied to designated public-interest purposes discourage them from participating actively. These rules should be relaxed to the extent that doing so does not compromise the goal of preventing concentrated economic power. Should the pending amendments to the Inheritance Tax and Gift Tax Act pass, public-interest corporations could emerge as significant providers of capital. Reflecting corporate impact investments in ESG assessments, or extending tax benefits tied to carbon-emission reductions, would also be worth exploring.
Impact idnetities, for their part, must become self-sufficient as for-profit enterprises. The appropriate aim is therefore not extensive dedicated support but assurance that they are not shut out of general support policies for small and medium-sized enterprises. Ecosystem infrastructure, however, does require public backing: dedicated organizations to support the production and dissemination of impact market information and to inform policy development, government support for standardized impact measurement tools and databases, and shared evaluation criteria built on a long-term perspective.
Conclusion
Korea’s impact investment market is moving beyond early stage of laying the foundation of eco-system and develop new framework capable of supporting scale-up of the industry.
Full-fledged growth, however, will require overcoming structural obstacles: an insufficient supply of capital, the absence of standardized social performance measurement, uncertainty around exits, and too few impact startups. Beneath these lie two more basic conditions — market foundations for the double bottom line model, which pursues financial return and social value together, that remain fragile, and an exit horizon longer than that of conventional venture capital.
Meeting these challenges will take work on three fronts. On the capital side, the pool of impact LPs needs to be enlarged and diversified, policy funds scaled up, tax incentives introduced, and long-term capital drawn from pension funds and insurance companies; public-private blended finance should be expanded and funding instruments diversified. On the exit side, secondary and public-market channels need strengthening. On the measurement side, social value measurement must be made objective and transparent, within a multi-layered system able to accommodate more than one definition of impact and more than one method of gauging it. Government policy support is critical throughout.
Financial return and social outcomes are not inherently at odds, and evidence is accumulating that the two can coexist where investment structures are designed with care. The task ahead is no longer to lay the groundwork for an impact investing ecosystem but to design a framework capable of carrying it through scale-up.