Our bi-weekly Opinion provides you with latest updates and analysis on major capital market and financial investment industry issues.

Korea’s Capital Market in 2026, with Investor Rights Protection Still Stuck in the 1960s: Reform Priorities for Unclaimed Shares and Bondholders’ Meetings
Publication date Aug. 25, 2026
Summary
By 2026, Korea’s capital market has made remarkable progress in both market scale and institutional development, as reflected in stock indices and market capitalization, the breadth of its retail investor base, amendments to the Commercial Act, and the electronic securities system. Yet the procedures through which investors recover lost rights and collectively exercise their rights in times of crisis remain anchored in a 1960s legal framework premised on physical share certificates and in-person procedures. This article examines problems in the procedures for reclaiming unclaimed shares and participating in bondholders’ meetings and sets out reform priorities.
Unclaimed shares numbered 34.34 million in 2025, and the extent of the neglect is underscored by the fact that shareholder registers contained more than 180,000 entries for shareholders aged 100 or older. Yet reclaiming these shares is excessively complex: a shareholder must complete the public summons and nullification judgment procedures under the Civil Procedure Act enacted in 1960 and appear in court in person. Reforms should extend jurisdiction over public summons applications to the district court for the applicant’s place of residence, enable remote proceedings through electronic litigation, introduce a simplified procedure for recovering rights to small shareholdings, and require notice of unclaimed dividends before the limitation period expires.
Bondholders’ meetings are likewise governed by the Commercial Act enacted in 1962: even in the era of electronic securities, in which physical bond certificates no longer exist, a holder of bearer bonds must make successive visits to the electronic registry (or account management institution), the deposit office, and the meeting venue to exercise voting rights, and the issuer has no legal basis for identifying its bondholders, creating a risk that the meeting will fail. Accordingly, the Commercial Act should be amended to allow a certificate of ownership to be submitted in lieu of depositing an electronic registration certificate, and the Act on Electronic Registration of Stocks and Bonds should be revised to expand the grounds on which a register of holders for bearer bonds may be prepared. Modernizing investors’ rights-exercise procedures to match the level of Korea’s 2026 capital market would close gaps in investor protection and strengthen confidence in the capital market.
Unclaimed shares numbered 34.34 million in 2025, and the extent of the neglect is underscored by the fact that shareholder registers contained more than 180,000 entries for shareholders aged 100 or older. Yet reclaiming these shares is excessively complex: a shareholder must complete the public summons and nullification judgment procedures under the Civil Procedure Act enacted in 1960 and appear in court in person. Reforms should extend jurisdiction over public summons applications to the district court for the applicant’s place of residence, enable remote proceedings through electronic litigation, introduce a simplified procedure for recovering rights to small shareholdings, and require notice of unclaimed dividends before the limitation period expires.
Bondholders’ meetings are likewise governed by the Commercial Act enacted in 1962: even in the era of electronic securities, in which physical bond certificates no longer exist, a holder of bearer bonds must make successive visits to the electronic registry (or account management institution), the deposit office, and the meeting venue to exercise voting rights, and the issuer has no legal basis for identifying its bondholders, creating a risk that the meeting will fail. Accordingly, the Commercial Act should be amended to allow a certificate of ownership to be submitted in lieu of depositing an electronic registration certificate, and the Act on Electronic Registration of Stocks and Bonds should be revised to expand the grounds on which a register of holders for bearer bonds may be prepared. Modernizing investors’ rights-exercise procedures to match the level of Korea’s 2026 capital market would close gaps in investor protection and strengthen confidence in the capital market.
By 2026, Korea’s capital market has reached global standards in both market scale and institutional development. The KOSPI posted the strongest gains among major global stock markets in 2025 and the first half of 2026, while Korea’s stock market capitalization climbed to around seventh place globally.1) Market participation has also expanded: the number of retail investors rose from 6.14 million in 2019 to 14.42 million by the end of 2025, meaning that more than one-quarter of the population held shares.2) Through three amendments to the Commercial Act spanning 2025 and 2026, long-debated measures to strengthen shareholder rights were written into law, and the electronic securities system, fully implemented in September 2019, has become core infrastructure for the issuance and circulation of securities and the exercise of related rights entirely by electronic means, without physical certificates.
Yet the procedures by which investors recover and exercise their rights have failed to keep pace with these changes. To recover the shares and dividends represented by lost physical share certificates, a shareholder must complete the public summons and nullification judgment procedures under the Civil Procedure Act enacted in 1960 and appear in court in person; likewise, an owner of electronically registered bonds must visit a deposit office before exercising voting rights at a bondholders’ meeting under the Commercial Act of 1962. As electronic shareholders’ meetings become mandatory, the procedures for recovering and exercising rights in shares and bonds remain governed by a legal framework designed more than sixty years ago on the premise of physical certificates and in-person procedures. Against this backdrop, this article examines the problems with reclaiming unclaimed shares and participating in bondholders’ meetings and sets out reform priorities.
Reclaiming Unclaimed Shares: Problems and Reform Priorities
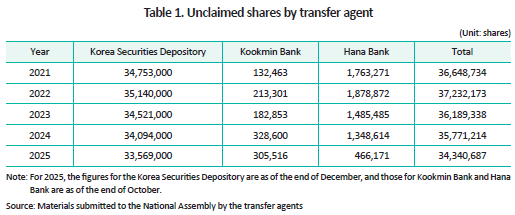
Shareholders are entitled to receive dividends from the company and to be allotted new shares when a bonus issue or stock dividend takes place. Today, under the electronic securities system, all listed shares must be held through securities accounts, preventing new cases from falling outside the depository system’s automatic account-crediting process. In the era of paper share certificates, however, it was common for ordinary shareholders—such as subscribers to “people’s shares”3)—to keep their certificates at home rather than deposit them with a securities company, with only their names entered in the shareholder register. Shares allotted to them were held in custody by transfer agents, which sent postal notices to the addresses recorded in the register. When notices failed to reach shareholders because of a change of address or the shareholder’s death, shareholders and their heirs might never learn that dividends had accrued or that additional shares had been allotted to them. Shares that accumulated unclaimed in this way over decades are referred to as unclaimed shares. With the implementation of the electronic securities system, listed companies’ share certificates were invalidated en bloc, but the holdings of shareholders who had retained physical certificates rather than depositing them with a securities company were recorded in special accounts managed by transfer agents, where they remain in custody. The number of unclaimed shares stood at 34.34 million in 2025.
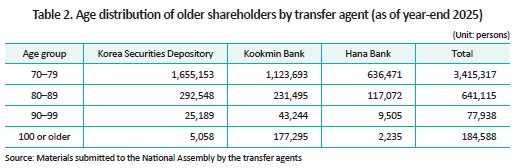
The age distribution recorded in shareholder registers warrants particular attention. As shown in Table 2, the shareholder registers maintained by the three transfer agents contained more than 184,000 entries for shareholders aged 100 or older at the end of 2025. By contrast, Ministry of the Interior and Safety resident-registration data show that only 8,726 residents were aged 100 or older at the end of 2025.4) Although the figures aggregate issuer-level shareholder registers and may therefore count the same person more than once, the fact that these entries exceed the actual population by more than twentyfold indicates that a substantial volume of shares remains unresolved after shareholders’ deaths, without completion of inheritance or share-transfer registration procedures.
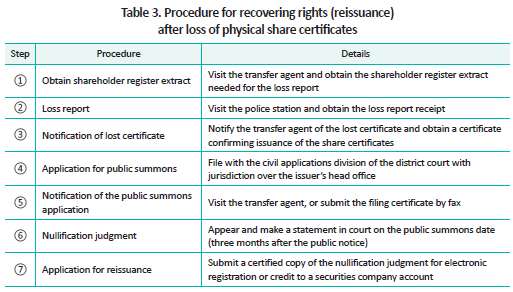
Although the Korea Securities Depository and other transfer agents have been running campaigns to return unclaimed shares to their owners,5) many shareholders still fail to recover their shares because the procedure is excessively complex. A shareholder listed on the register who has lost physical share certificates can invalidate them and recover the underlying rights only after reporting the loss to the transfer agent and completing public summons and nullification judgment procedures; these procedures have remained essentially unchanged since they were codified in the Civil Procedure Act enacted in 1960 (Articles 475 through 497 of the Civil Procedure Act). As shown in Table 3, the shareholder must complete a seven-step procedure involving successive visits to the transfer agent, the police station, and the court, taking roughly three to four months. The public summons date must be set at least three months after the end of the public notice (Article 481 of the Civil Procedure Act), and jurisdiction lies not with the district court for the shareholder’s residence but with the district court for the place where the issuer’s head office is located (proviso to Article 476(2) of the Civil Procedure Act), so that a shareholder seeking to recover even a small holding must visit the court at the company’s head-office location at least once. Even when the public summons application is filed electronically, the shareholder must still appear in court in person for the nullification judgment. It is extremely difficult, in particular, for elderly shareholders to assemble documents such as the shareholder register extract, the loss report receipt, the share certificate issuance confirmation, and the certificate of corporate registration and complete this procedure, and in practice there have been cases of shareholders abandoning their rights because of the complexity of the process.
Even if a shareholder gives up on recovering the shares, dividends continue to accrue and remain with the transfer agent. As Table 4 shows, approximately KRW 1.1 billion to KRW 1.6 billion in dividends remains unclaimed each year. In practice, the transfer agent holds unclaimed dividends for five years from the date dividend payments begin and then returns them to the company, because a dividend payment claim becomes time-barred if not exercised for five years (Article 464-2(2) of the Commercial Act). Shareholders may not even be notified that dividends are owed to them and therefore may be unable to exercise their claims—a structure in which five years of silence ultimately benefits the company. From the issuer’s perspective, if shareholders do not exercise their rights the company need not pay the dividends, so it has little practical incentive to actively locate its shareholders.

To enable shareholders to recover their legitimate rights to these unclaimed shares and dividends, the procedure must be made faster and more accessible. Jurisdiction over public summons applications should be extended to the district court for the applicant’s place of residence, and electronic litigation procedures should be revised to permit public summons and nullification judgment proceedings to be conducted remotely. Furthermore, in the electronic securities era—when rights holders can be verified through the shareholder register and the electronic registration account book—the introduction of a simplified special procedure could be considered for small shareholdings, allowing rights to be recovered through confirmation by the transfer agent and the electronic registry without prior recourse to judicial proceedings. In addition, issuers and transfer agents should be required to periodically notify shareholders with long-outstanding unclaimed dividends before the limitation period expires. Rather than allowing time-barred dividends to revert to the issuer, consideration should be given to transferring them to a public body, as under the dormant-deposit scheme, and allowing shareholders to claim repayment without any time limit.
Participation in Bondholders’ Meetings: Problems and Reform Priorities
Bondholders’ exercise of rights is likewise governed by the Commercial Act enacted in 1962. A bondholders’ meeting is convened when matters arise that materially affect bondholders’ interests, such as acceleration (loss of the benefit of time) or modification of the terms of the debt; yet a holder of bearer bonds may not exercise voting rights unless the bonds are deposited no later than one week before the meeting (Article 492(2) of the Commercial Act). The place of deposit, moreover, is with a “deposit officer, or a bank or trust company designated by the Chief Justice of the Supreme Court,” as prescribed in the Addenda to the Commercial Act of 1962.6) In the electronic securities era, in which no physical bond certificates exist, a provision premised on the deposit of physical certificates remains intact. Although the deposit requirement applies only to bearer bonds, virtually all corporate bonds in Korea are issued in bearer form,7) with the result that the requirement effectively constrains the voting rights of nearly all bondholders.
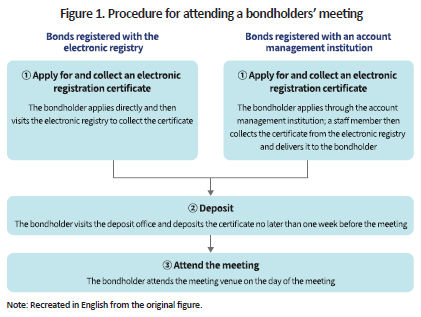
Moreover, with physical certificates having disappeared following the implementation of the electronic securities system in 2019, bondholders now deposit electronic registration certificates in lieu of bond certificates, making the process exceptionally cumbersome. As shown in Figure 1, to attend a meeting and exercise their rights collectively during a corporate crisis, bondholders must visit three locations in sequence: the electronic registry (or account management institution), the deposit office, and the bondholders’ meeting venue. Even without physical certificates, bondholders must still complete three separate in-person steps. This stands in stark contrast to the framework for shareholders’ voting rights: electronic voting is now widespread, and large listed companies will be required to hold hybrid electronic shareholders’ meetings from 2027.
There are problems from the issuer’s perspective as well. Article 37(3) of the Act on Electronic Registration of Stocks and Bonds limits preparation of a register of holders for bearer securities to cases such as the conversion of contingent capital securities into shares, leaving an issuer without a legal means of identifying its bondholders even when it convenes a bondholders’ meeting. In practice, issuers send official letters to the customer service centers and branch offices of all securities companies and identify bondholders individually by telephone. Indeed, in the cases of the Doosan Infracore spin-off and subsequent merger (2021), the Taeyoung Engineering & Construction debt-for-equity swap (2024), and the Lotte Chemical acceleration event (2024), the absence of a legal basis for preparing a register of holders caused difficulties in identifying bondholders; and although the Financial Services Commission announced in 2023 a plan to enable bonds, like shares, to be processed electronically in M&A transactions, it did not lead to legislation.8) From the bondholders’ side as well, a public notice issued only three weeks before the meeting may not reach them; in one case, a company had to publish repeated notices for the same meeting.9) If attendance at a bondholders’ meeting is low, the meeting may fail to satisfy the statutory voting thresholds—approval by at least two-thirds of the voting rights represented at the meeting and by votes representing at least one-third of the total principal amount of the bonds (Article 495(1) of the Commercial Act). If a meeting convened to prevent acceleration fails, both bondholders and the company bear the loss.
To resolve these problems, the deposit requirement for participation in bondholders’ meetings should first be overhauled: Articles 491 and 492 of the Commercial Act should be amended so that, for electronically registered bonds, submission of a certificate of ownership suffices in lieu of the deposit. Because proof of ownership is sufficient to participate in a bondholders’ meeting and the certificate need not have the legal effect of a negotiable instrument, bondholders should be able to request that a meeting be convened and exercise voting rights by submitting to the company or the bond administration company a certificate of ownership obtained through their account management institution. In addition, Article 37 of the Act on Electronic Registration of Stocks and Bonds should be amended to add, as grounds for preparing a register of holders for bearer bonds, creditor protection procedures for mergers and spin-offs and the convocation of bondholders’ meetings. Prompt identification would enable issuers and bond administration companies to consult bondholders in advance during an acceleration crisis and would give creditors a meaningful opportunity to raise objections. Over the longer term, consideration should also be given to introducing a book-entry deposit mechanism, thereby eliminating paper electronic registration certificates, and allowing bondholders’ meetings to be conducted electronically along lines similar to electronic shareholders’ meetings.
The amendments to the Commercial Act enacted in 2025 and 2026 have greatly improved shareholder protection, but the procedures for investors to recover lost rights and for bondholders to exercise their rights collectively in times of crisis remain confined to systems designed in the 1960s. The reality that more than 180,000 shareholders aged 100 or older were listed in shareholder registers as of 2025, and that a bondholder must visit three different institutions to exercise a single vote, is out of keeping with the capital market of 2026. With the generation that subscribed to “people’s shares” already elderly, the longer institutional reform is delayed, the more investors will be unable to recover their rights. Aligning investors’ rights-exercise procedures with the level of Korea’s 2026 capital market will not only close remaining gaps in investor protection but also strengthen confidence in the capital market.
1) Financial Services Commission, Jul. 15, 2026, FSC Work Report, press release.
2) Korea Securities Depository, Mar. 18, 2026, Share Ownership of Listed Companies with Fiscal Years Ending in December 2025, press release; National Data Office, Jul. 28, 2026, Results of the 2025 Population and Housing Census, press release.
3) As part of its policy to broaden the base of stock market investors, the government sold its shareholdings in representative public enterprises—POSCO (1988) and Korea Electric Power Corporation (1989)—to the public as "people’s shares" (see the National Archives of Korea website).
4) Ministry of the Interior and Safety, resident registration demographics (jumin.mois.go.kr/ageStatMonth.do).
5) Korea Securities Depository, Oct. 23, 2025, KSD Successfully Completes the 2025 Intensive Campaign to Return Unclaimed Shares, press release.
6) The Commercial Act, enacted on January 20, 1962, referred to a warehouse business operator; an amendment on December 12 of the same year replaced that term with a trust company.
7) Yoon, Y., 2021, Legal Issues in Exercising Rights in Electronically Registered Shares and Bearer Bonds, and Proposals to Amend the Act on Electronic Registration of Stocks and Bonds and the Commercial Act, Chung-Ang Law Review 45(3), 187-210.
8) Financial Services Commission, May 8, 2023, Plan to Support Corporate M&A, press release.
9) In 2023, ASTK gave public notice of the convocation of a bondholders’ meeting in November and then gave notice again for the same meeting in December and the following January.
Yet the procedures by which investors recover and exercise their rights have failed to keep pace with these changes. To recover the shares and dividends represented by lost physical share certificates, a shareholder must complete the public summons and nullification judgment procedures under the Civil Procedure Act enacted in 1960 and appear in court in person; likewise, an owner of electronically registered bonds must visit a deposit office before exercising voting rights at a bondholders’ meeting under the Commercial Act of 1962. As electronic shareholders’ meetings become mandatory, the procedures for recovering and exercising rights in shares and bonds remain governed by a legal framework designed more than sixty years ago on the premise of physical certificates and in-person procedures. Against this backdrop, this article examines the problems with reclaiming unclaimed shares and participating in bondholders’ meetings and sets out reform priorities.
Reclaiming Unclaimed Shares: Problems and Reform Priorities
Shareholders are entitled to receive dividends from the company and to be allotted new shares when a bonus issue or stock dividend takes place. Today, under the electronic securities system, all listed shares must be held through securities accounts, preventing new cases from falling outside the depository system’s automatic account-crediting process. In the era of paper share certificates, however, it was common for ordinary shareholders—such as subscribers to “people’s shares”3)—to keep their certificates at home rather than deposit them with a securities company, with only their names entered in the shareholder register. Shares allotted to them were held in custody by transfer agents, which sent postal notices to the addresses recorded in the register. When notices failed to reach shareholders because of a change of address or the shareholder’s death, shareholders and their heirs might never learn that dividends had accrued or that additional shares had been allotted to them. Shares that accumulated unclaimed in this way over decades are referred to as unclaimed shares. With the implementation of the electronic securities system, listed companies’ share certificates were invalidated en bloc, but the holdings of shareholders who had retained physical certificates rather than depositing them with a securities company were recorded in special accounts managed by transfer agents, where they remain in custody. The number of unclaimed shares stood at 34.34 million in 2025.
The age distribution recorded in shareholder registers warrants particular attention. As shown in Table 2, the shareholder registers maintained by the three transfer agents contained more than 184,000 entries for shareholders aged 100 or older at the end of 2025. By contrast, Ministry of the Interior and Safety resident-registration data show that only 8,726 residents were aged 100 or older at the end of 2025.4) Although the figures aggregate issuer-level shareholder registers and may therefore count the same person more than once, the fact that these entries exceed the actual population by more than twentyfold indicates that a substantial volume of shares remains unresolved after shareholders’ deaths, without completion of inheritance or share-transfer registration procedures.
Although the Korea Securities Depository and other transfer agents have been running campaigns to return unclaimed shares to their owners,5) many shareholders still fail to recover their shares because the procedure is excessively complex. A shareholder listed on the register who has lost physical share certificates can invalidate them and recover the underlying rights only after reporting the loss to the transfer agent and completing public summons and nullification judgment procedures; these procedures have remained essentially unchanged since they were codified in the Civil Procedure Act enacted in 1960 (Articles 475 through 497 of the Civil Procedure Act). As shown in Table 3, the shareholder must complete a seven-step procedure involving successive visits to the transfer agent, the police station, and the court, taking roughly three to four months. The public summons date must be set at least three months after the end of the public notice (Article 481 of the Civil Procedure Act), and jurisdiction lies not with the district court for the shareholder’s residence but with the district court for the place where the issuer’s head office is located (proviso to Article 476(2) of the Civil Procedure Act), so that a shareholder seeking to recover even a small holding must visit the court at the company’s head-office location at least once. Even when the public summons application is filed electronically, the shareholder must still appear in court in person for the nullification judgment. It is extremely difficult, in particular, for elderly shareholders to assemble documents such as the shareholder register extract, the loss report receipt, the share certificate issuance confirmation, and the certificate of corporate registration and complete this procedure, and in practice there have been cases of shareholders abandoning their rights because of the complexity of the process.
Even if a shareholder gives up on recovering the shares, dividends continue to accrue and remain with the transfer agent. As Table 4 shows, approximately KRW 1.1 billion to KRW 1.6 billion in dividends remains unclaimed each year. In practice, the transfer agent holds unclaimed dividends for five years from the date dividend payments begin and then returns them to the company, because a dividend payment claim becomes time-barred if not exercised for five years (Article 464-2(2) of the Commercial Act). Shareholders may not even be notified that dividends are owed to them and therefore may be unable to exercise their claims—a structure in which five years of silence ultimately benefits the company. From the issuer’s perspective, if shareholders do not exercise their rights the company need not pay the dividends, so it has little practical incentive to actively locate its shareholders.
To enable shareholders to recover their legitimate rights to these unclaimed shares and dividends, the procedure must be made faster and more accessible. Jurisdiction over public summons applications should be extended to the district court for the applicant’s place of residence, and electronic litigation procedures should be revised to permit public summons and nullification judgment proceedings to be conducted remotely. Furthermore, in the electronic securities era—when rights holders can be verified through the shareholder register and the electronic registration account book—the introduction of a simplified special procedure could be considered for small shareholdings, allowing rights to be recovered through confirmation by the transfer agent and the electronic registry without prior recourse to judicial proceedings. In addition, issuers and transfer agents should be required to periodically notify shareholders with long-outstanding unclaimed dividends before the limitation period expires. Rather than allowing time-barred dividends to revert to the issuer, consideration should be given to transferring them to a public body, as under the dormant-deposit scheme, and allowing shareholders to claim repayment without any time limit.
Participation in Bondholders’ Meetings: Problems and Reform Priorities
Bondholders’ exercise of rights is likewise governed by the Commercial Act enacted in 1962. A bondholders’ meeting is convened when matters arise that materially affect bondholders’ interests, such as acceleration (loss of the benefit of time) or modification of the terms of the debt; yet a holder of bearer bonds may not exercise voting rights unless the bonds are deposited no later than one week before the meeting (Article 492(2) of the Commercial Act). The place of deposit, moreover, is with a “deposit officer, or a bank or trust company designated by the Chief Justice of the Supreme Court,” as prescribed in the Addenda to the Commercial Act of 1962.6) In the electronic securities era, in which no physical bond certificates exist, a provision premised on the deposit of physical certificates remains intact. Although the deposit requirement applies only to bearer bonds, virtually all corporate bonds in Korea are issued in bearer form,7) with the result that the requirement effectively constrains the voting rights of nearly all bondholders.
Moreover, with physical certificates having disappeared following the implementation of the electronic securities system in 2019, bondholders now deposit electronic registration certificates in lieu of bond certificates, making the process exceptionally cumbersome. As shown in Figure 1, to attend a meeting and exercise their rights collectively during a corporate crisis, bondholders must visit three locations in sequence: the electronic registry (or account management institution), the deposit office, and the bondholders’ meeting venue. Even without physical certificates, bondholders must still complete three separate in-person steps. This stands in stark contrast to the framework for shareholders’ voting rights: electronic voting is now widespread, and large listed companies will be required to hold hybrid electronic shareholders’ meetings from 2027.
There are problems from the issuer’s perspective as well. Article 37(3) of the Act on Electronic Registration of Stocks and Bonds limits preparation of a register of holders for bearer securities to cases such as the conversion of contingent capital securities into shares, leaving an issuer without a legal means of identifying its bondholders even when it convenes a bondholders’ meeting. In practice, issuers send official letters to the customer service centers and branch offices of all securities companies and identify bondholders individually by telephone. Indeed, in the cases of the Doosan Infracore spin-off and subsequent merger (2021), the Taeyoung Engineering & Construction debt-for-equity swap (2024), and the Lotte Chemical acceleration event (2024), the absence of a legal basis for preparing a register of holders caused difficulties in identifying bondholders; and although the Financial Services Commission announced in 2023 a plan to enable bonds, like shares, to be processed electronically in M&A transactions, it did not lead to legislation.8) From the bondholders’ side as well, a public notice issued only three weeks before the meeting may not reach them; in one case, a company had to publish repeated notices for the same meeting.9) If attendance at a bondholders’ meeting is low, the meeting may fail to satisfy the statutory voting thresholds—approval by at least two-thirds of the voting rights represented at the meeting and by votes representing at least one-third of the total principal amount of the bonds (Article 495(1) of the Commercial Act). If a meeting convened to prevent acceleration fails, both bondholders and the company bear the loss.
To resolve these problems, the deposit requirement for participation in bondholders’ meetings should first be overhauled: Articles 491 and 492 of the Commercial Act should be amended so that, for electronically registered bonds, submission of a certificate of ownership suffices in lieu of the deposit. Because proof of ownership is sufficient to participate in a bondholders’ meeting and the certificate need not have the legal effect of a negotiable instrument, bondholders should be able to request that a meeting be convened and exercise voting rights by submitting to the company or the bond administration company a certificate of ownership obtained through their account management institution. In addition, Article 37 of the Act on Electronic Registration of Stocks and Bonds should be amended to add, as grounds for preparing a register of holders for bearer bonds, creditor protection procedures for mergers and spin-offs and the convocation of bondholders’ meetings. Prompt identification would enable issuers and bond administration companies to consult bondholders in advance during an acceleration crisis and would give creditors a meaningful opportunity to raise objections. Over the longer term, consideration should also be given to introducing a book-entry deposit mechanism, thereby eliminating paper electronic registration certificates, and allowing bondholders’ meetings to be conducted electronically along lines similar to electronic shareholders’ meetings.
The amendments to the Commercial Act enacted in 2025 and 2026 have greatly improved shareholder protection, but the procedures for investors to recover lost rights and for bondholders to exercise their rights collectively in times of crisis remain confined to systems designed in the 1960s. The reality that more than 180,000 shareholders aged 100 or older were listed in shareholder registers as of 2025, and that a bondholder must visit three different institutions to exercise a single vote, is out of keeping with the capital market of 2026. With the generation that subscribed to “people’s shares” already elderly, the longer institutional reform is delayed, the more investors will be unable to recover their rights. Aligning investors’ rights-exercise procedures with the level of Korea’s 2026 capital market will not only close remaining gaps in investor protection but also strengthen confidence in the capital market.
1) Financial Services Commission, Jul. 15, 2026, FSC Work Report, press release.
2) Korea Securities Depository, Mar. 18, 2026, Share Ownership of Listed Companies with Fiscal Years Ending in December 2025, press release; National Data Office, Jul. 28, 2026, Results of the 2025 Population and Housing Census, press release.
3) As part of its policy to broaden the base of stock market investors, the government sold its shareholdings in representative public enterprises—POSCO (1988) and Korea Electric Power Corporation (1989)—to the public as "people’s shares" (see the National Archives of Korea website).
4) Ministry of the Interior and Safety, resident registration demographics (jumin.mois.go.kr/ageStatMonth.do).
5) Korea Securities Depository, Oct. 23, 2025, KSD Successfully Completes the 2025 Intensive Campaign to Return Unclaimed Shares, press release.
6) The Commercial Act, enacted on January 20, 1962, referred to a warehouse business operator; an amendment on December 12 of the same year replaced that term with a trust company.
7) Yoon, Y., 2021, Legal Issues in Exercising Rights in Electronically Registered Shares and Bearer Bonds, and Proposals to Amend the Act on Electronic Registration of Stocks and Bonds and the Commercial Act, Chung-Ang Law Review 45(3), 187-210.
8) Financial Services Commission, May 8, 2023, Plan to Support Corporate M&A, press release.
9) In 2023, ASTK gave public notice of the convocation of a bondholders’ meeting in November and then gave notice again for the same meeting in December and the following January.