Our bi-weekly Opinion provides you with latest updates and analysis on major capital market and financial investment industry issues.

Retail Investors' Leveraged Investment: Current Status and Implications
Publication date Aug. 25, 2026
Summary
Since 2025, Korean stock indices have risen sharply and become more volatile, and as a result, leveraged investment by retail investors has been growing quickly. As of the end of June 2026, the outstanding balance of margin loans in Korea stood at 36.7 trillion won, 5.5 times the level at the end of 2016. This growth is 1.7 times faster than the growth of margin trading in the United States. Over the same period, the total net assets of leveraged ETFs that track ±2 times an underlying index also rose 13.1 times, to 39.4 trillion won, while the balances of unsettled-payment trading and CFDs increased by 57% and 60%, respectively, compared with the end of 2024.
Retail investors who buy leveraged products can suffer large losses if the underlying asset moves in the opposite direction from their position, and those losses can grow even larger because of high interest costs, management fees, and negative compounding effects. In particular, if forced liquidations occur one after another in margin loans and unsettled-payment trading, or if the hedging trades of leveraged ETFs are concentrated near the market close, volatility across the whole stock market may increase. Accordingly, this article proposes the following medium- to long-term tasks for protecting retail investors and strengthening financial stability.
First, it is necessary to consider tightening the entry rules for high-risk leveraged products. Second, to strengthen financial stability, the outstanding balance of margin loans and the net assets of leveraged ETFs need to be monitored closely. Third, tax incentives should be used to broaden the base of long-term institutional investors, and financial education should be strengthened across the entire life cycle.
Retail investors who buy leveraged products can suffer large losses if the underlying asset moves in the opposite direction from their position, and those losses can grow even larger because of high interest costs, management fees, and negative compounding effects. In particular, if forced liquidations occur one after another in margin loans and unsettled-payment trading, or if the hedging trades of leveraged ETFs are concentrated near the market close, volatility across the whole stock market may increase. Accordingly, this article proposes the following medium- to long-term tasks for protecting retail investors and strengthening financial stability.
First, it is necessary to consider tightening the entry rules for high-risk leveraged products. Second, to strengthen financial stability, the outstanding balance of margin loans and the net assets of leveraged ETFs need to be monitored closely. Third, tax incentives should be used to broaden the base of long-term institutional investors, and financial education should be strengthened across the entire life cycle.
Current Status of Retail Investors’ Leveraged Investment
Leveraged investment by retail investors has been increasing rapidly in recent years. Helped by improved earnings in the semiconductor sector, an increase in global liquidity, and the new government's policies to revitalize the capital market, the KOSPI index rose 176% over the one-year period ending in June 2026 — the highest return among major stock markets.1) As the KOSPI climbed, more retail investors entered the market in search of high returns, and leveraged investment — such as margin loans and ETFs that track ±2 times an underlying index — expanded quickly.
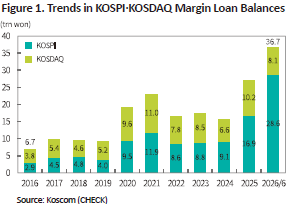
Retail investors' leveraged investment is growing fastest in margin loans. At the end of June 2026, the outstanding balance of margin loans in the Korean stock market was 36.7 trillion won, 5.5 times the 6.7 trillion won recorded at the end of 2016; this corresponds to an average annual growth rate of 19.6% (see Figure 1). Over the same period, margin accounts in the U.S. stock market grew from 530 billion dollars to 1,502.1 billion dollars — a 2.8-fold increase, or 11.6% per year on average.2) Compared with this, margin loans in Korea have been growing about twice as fast as in the United States. There has also been a clear change in how margin loans are distributed across markets. During the COVID-19 period of 2020–2021, the margin loan balance rose to roughly 20 trillion won, more than double the level at the end of 2019, and at that time the KOSDAQ market accounted for about half of the total. By contrast, at the end of June 2026, margin loan balances in the KOSPI and KOSDAQ markets were 28.6 trillion won and 8.1 trillion won respectively, meaning the KOSPI market makes up 78% of the total. In other words, the recent increase in margin loans is centered on large-cap KOSPI stocks rather than small- and mid-cap KOSDAQ stocks, which suggests that leverage is becoming concentrated in particular sectors, such as semiconductors, where returns are highly volatile.
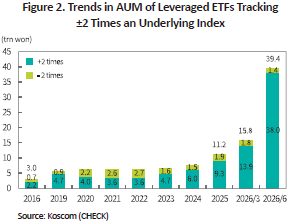
The expansion of retail investors' leveraged investment can also be seen in the leveraged ETF market. The total net assets (AUM) of Korean leveraged ETFs that track twice the return of an underlying index reached 39.4 trillion won at the end of June 2026, 13.1 times the 3.0 trillion won recorded at the end of 2016; this corresponds to an average annual growth rate of 31.1% (see Figure 2). In the global ETF market, leveraged ETF AUM grew from roughly 50–60 billion dollars (end of 2016) to 198 billion dollars (end of June 2026), an average annual increase of around 15%. Compared with this, the growth of Korean leveraged ETF AUM has also been very fast. Recently, there has been a clear change in the underlying assets of Korean leveraged ETFs as well. In the past, domestic leveraged ETFs grew mainly around products that tracked twice the return of stock indices such as the KOSPI 200. However, since single-stock leveraged ETFs were listed in the first half of 2026, products using individual stocks as the underlying asset have been leading the growth. Because individual stocks are more volatile than stock indices, the risk borne by investors becomes considerably larger even when the same multiple is applied. Meanwhile, the AUM of inverse leveraged ETFs, which track minus two times the return of an underlying index, stood at 1.4 trillion won at the end of June 2026, only 3.5% of all leveraged ETFs. This suggests that retail investors are using leveraged ETFs mainly to bet one-directionally on rising stock prices rather than to diversify risk.
Besides margin loans and leveraged ETFs, other leveraged transactions by retail investors — such as unsettled-payment trading and contracts for difference (CFDs) — have also been growing quickly. At the end of June 2026, the balances of brokerage unsettled-payment trading and CFDs at Korean securities firms were 1.4 trillion won and 1.9 trillion won respectively, up 57% and 60% from 0.9 trillion won and 1.2 trillion won at the end of 2024. This expansion of leveraged investment not only increases retail investors' losses when the underlying index moves in the opposite direction, but also requires caution because it can amplify market volatility through forced liquidations and institutional investors' hedging trades when stock prices correct.3) This article therefore examines the risk factors of leveraged investment and explores medium- to long-term measures to strengthen investor protection and financial stability.
Risk Factors of Leveraged Investment
Margin loan trading carries a high effective leverage ratio and can therefore magnify retail investors' losses. In a margin loan, the investor pays only 45–60% of the purchase amount as a margin deposit (as an example) and borrows the rest from a securities firm to buy stocks, which results in an effective leverage ratio of around 2 times. Assuming a deposit ratio of 45%, if the purchased stock falls 30%, the investor's actual loss rate reaches 67% — 2.22 times the 30% decline — and if the stock falls 45%, the investor can lose the entire principal. In addition, margin transactions are usually contracts that require repayment within 90 days, and margin loan interest rates tend to be high, so unless the stock price rises substantially within the agreed period, the investor incurs a loss equal to the interest cost. The most worrying risk is the risk of price declines caused by forced liquidations. If the stock price falls below the collateral maintenance ratio, forced selling is triggered, and the resulting supply of shares can accelerate the decline further, potentially creating a vicious cycle in which margin positions taken at successively lower price levels are liquidated one after another. In such a case, retail investors' losses can spill over into higher volatility for the market as a whole, so caution is needed.
Leveraged ETFs also require caution, as they can enlarge retail investors' losses and increase market volatility. Because leveraged ETFs track ±2 times the return of an underlying index, losses double if the index moves in the opposite direction from the investor's position. On top of this come losses caused by negative compounding. If an index rises 20% and then falls 20%, the loss based on the index is only 4%; but a 2x leveraged ETF rises 40% and then falls 40%, so the loss widens to 16%. Leveraged ETFs also charge higher management fees than ordinary ETFs and show larger tracking errors and price–NAV divergences, so investors may bear additional costs unrelated to the return of the underlying index. Furthermore, the hedging process of leveraged ETFs creates demand to trade ±2 times the underlying index, which can increase the index's volatility.4) In particular, when the index rises or falls sharply, sizeable hedging volumes have to be bought or sold near the market close, which may add further to the index's volatility.5)
High-multiple leveraged products such as unsettled-payment trading, CFDs, and futures and options carry an even greater risk of loss than margin loans or leveraged ETFs. This is because these products not only have high leverage multiples but also leave very little time before losses are locked in. In unsettled-payment trading, the purchase amount must be paid within two business days, the settlement date; if it is not paid, forced selling is executed on the next business day, so the investor has virtually no room to wait for the price to recover. CFDs and futures and options trading require daily mark-to-market settlement to maintain the margin level, so if the margin falls below the maintenance level the investor is immediately asked to deposit more, and forced liquidation follows if they cannot do so. In particular, when stock prices fall sharply, forced selling from these products tends to be concentrated, which in turn causes further price declines and can spread into greater volatility across the entire stock market.
Medium- to Long-Term Tasks to Curb Overheating in Leveraged Products
To minimize the side effects of overheated investment in leveraged products — including the higher risk of losses for retail investors and the possibility of greater stock market volatility — this article proposes measures to strengthen investor protection, improve financial stability, and broaden the base of long-term institutional investors.
First, in order to curb indiscriminate leveraged investment by retail investors, it is necessary to consider tightening entry rules for high-risk leveraged products. Financial companies should be encouraged to observe the appropriateness principle strictly, so that disclosure of risks is strengthened for retail investors with a low capacity to absorb losses and so that firms refrain from marketing and other forms of investment solicitation for leveraged products. It is also worth considering a system that identifies, on a semi-annual or annual basis, accounts that have accumulated losses from leveraged investment, strengthens risk disclosure for them, and keeps the share of leveraged investment within a certain proportion of total investment assets. From this perspective, the financial authorities' recent decision to pursue a total-volume management scheme that limits each individual's investment in single-stock leveraged ETFs to within 20% of their total investment amount is a positive step. However, if relatively strict rules are applied only to particular products, a balloon effect may occur in which demand shifts to other leveraged products at home and abroad. Over the medium to long term, it would therefore be desirable to build a consistent regulatory framework covering all leveraged products.
Second, to improve financial stability, close monitoring is needed so that the size of leveraged products does not become excessive. Specifically, where there is a possibility of greater instability in financial markets, authorities could look for ways to keep the margin loan balance and the total net assets of leveraged ETFs within certain levels. This is because, if forced liquidations occur when margin loans have grown excessively large, price declines accelerate, and those declines in turn trigger more forced selling, acting as a catalyst for greater volatility. Likewise, if leveraged ETFs grow too large and the underlying index falls sharply, large hedging volumes released near the close may increase price volatility. In this regard, the financial authorities' move to introduce emergency powers — such as lowering leverage multiples when markets swing sharply — by drawing on the reform case of Hong Kong's Securities and Futures Commission is expected to contribute to greater financial market stability.6)
Third, institutional improvements are needed to build a culture of long-term investment among retail investors. Since the expansion of leveraged investment is closely linked to trading practices centered on short-term buying and selling, a fundamental solution requires an institutional foundation that encourages long-term, diversified investment. To this end, it is necessary to improve the competitiveness of public funds and to reform the retirement pension and ISA systems in order to expand the market participation of domestic long-term institutional investors. Drawing on Japan's example of raising the annual contribution limit for NISA and extending the tax-free period indefinitely, Korea should consider substantially expanding the tax benefits of the ISA and personal pension systems. In addition, a structure in which tax benefits grow the longer shares are held would help reduce incentives for short-term trading and encourage long-term holding. Introducing a fund-type structure for retirement pensions and improving the substance of the default option are also important tasks, as they would widen the channels through which long-term money flows steadily into the capital market. Finally, financial education should be strengthened across the entire life cycle — from adolescence through middle age and old age — to make people aware of the risks of short-term leveraged investment and to encourage them to invest a portion of their surplus funds in a diversified way over long periods, thereby supporting individuals' asset building.
1) Between July 1, 2025 and June 30, 2026, the KOSPI rose 176%, while returns were 107% for Taiwan’s TAIEX, 73% for Japan’s Nikkei, 29% for the U.S. NASDAQ, 20% for the UK’s FTSE, and 19% for China’s Shanghai Composite.
2) See https://www.finra.org/rules-guidance/key-topics/margin-accounts/margin-statistics
3) See Jang (2026)
4) See Jang (2026)
5) See Jang (2026)
6) See https://apps.sfc.hk/edistributionWeb/gateway/EN/news-and-announcements/news/doc?refNo=26PR115
References
Jang, Keunhyeok, 2026, Stock Market Trends Before and After the Launch of Single-Stock Leveraged and Inverse ETFs and Their Implications, Capital Market Focus No. 2026-13.
Leveraged investment by retail investors has been increasing rapidly in recent years. Helped by improved earnings in the semiconductor sector, an increase in global liquidity, and the new government's policies to revitalize the capital market, the KOSPI index rose 176% over the one-year period ending in June 2026 — the highest return among major stock markets.1) As the KOSPI climbed, more retail investors entered the market in search of high returns, and leveraged investment — such as margin loans and ETFs that track ±2 times an underlying index — expanded quickly.
Retail investors' leveraged investment is growing fastest in margin loans. At the end of June 2026, the outstanding balance of margin loans in the Korean stock market was 36.7 trillion won, 5.5 times the 6.7 trillion won recorded at the end of 2016; this corresponds to an average annual growth rate of 19.6% (see Figure 1). Over the same period, margin accounts in the U.S. stock market grew from 530 billion dollars to 1,502.1 billion dollars — a 2.8-fold increase, or 11.6% per year on average.2) Compared with this, margin loans in Korea have been growing about twice as fast as in the United States. There has also been a clear change in how margin loans are distributed across markets. During the COVID-19 period of 2020–2021, the margin loan balance rose to roughly 20 trillion won, more than double the level at the end of 2019, and at that time the KOSDAQ market accounted for about half of the total. By contrast, at the end of June 2026, margin loan balances in the KOSPI and KOSDAQ markets were 28.6 trillion won and 8.1 trillion won respectively, meaning the KOSPI market makes up 78% of the total. In other words, the recent increase in margin loans is centered on large-cap KOSPI stocks rather than small- and mid-cap KOSDAQ stocks, which suggests that leverage is becoming concentrated in particular sectors, such as semiconductors, where returns are highly volatile.
The expansion of retail investors' leveraged investment can also be seen in the leveraged ETF market. The total net assets (AUM) of Korean leveraged ETFs that track twice the return of an underlying index reached 39.4 trillion won at the end of June 2026, 13.1 times the 3.0 trillion won recorded at the end of 2016; this corresponds to an average annual growth rate of 31.1% (see Figure 2). In the global ETF market, leveraged ETF AUM grew from roughly 50–60 billion dollars (end of 2016) to 198 billion dollars (end of June 2026), an average annual increase of around 15%. Compared with this, the growth of Korean leveraged ETF AUM has also been very fast. Recently, there has been a clear change in the underlying assets of Korean leveraged ETFs as well. In the past, domestic leveraged ETFs grew mainly around products that tracked twice the return of stock indices such as the KOSPI 200. However, since single-stock leveraged ETFs were listed in the first half of 2026, products using individual stocks as the underlying asset have been leading the growth. Because individual stocks are more volatile than stock indices, the risk borne by investors becomes considerably larger even when the same multiple is applied. Meanwhile, the AUM of inverse leveraged ETFs, which track minus two times the return of an underlying index, stood at 1.4 trillion won at the end of June 2026, only 3.5% of all leveraged ETFs. This suggests that retail investors are using leveraged ETFs mainly to bet one-directionally on rising stock prices rather than to diversify risk.
Besides margin loans and leveraged ETFs, other leveraged transactions by retail investors — such as unsettled-payment trading and contracts for difference (CFDs) — have also been growing quickly. At the end of June 2026, the balances of brokerage unsettled-payment trading and CFDs at Korean securities firms were 1.4 trillion won and 1.9 trillion won respectively, up 57% and 60% from 0.9 trillion won and 1.2 trillion won at the end of 2024. This expansion of leveraged investment not only increases retail investors' losses when the underlying index moves in the opposite direction, but also requires caution because it can amplify market volatility through forced liquidations and institutional investors' hedging trades when stock prices correct.3) This article therefore examines the risk factors of leveraged investment and explores medium- to long-term measures to strengthen investor protection and financial stability.
Risk Factors of Leveraged Investment
Margin loan trading carries a high effective leverage ratio and can therefore magnify retail investors' losses. In a margin loan, the investor pays only 45–60% of the purchase amount as a margin deposit (as an example) and borrows the rest from a securities firm to buy stocks, which results in an effective leverage ratio of around 2 times. Assuming a deposit ratio of 45%, if the purchased stock falls 30%, the investor's actual loss rate reaches 67% — 2.22 times the 30% decline — and if the stock falls 45%, the investor can lose the entire principal. In addition, margin transactions are usually contracts that require repayment within 90 days, and margin loan interest rates tend to be high, so unless the stock price rises substantially within the agreed period, the investor incurs a loss equal to the interest cost. The most worrying risk is the risk of price declines caused by forced liquidations. If the stock price falls below the collateral maintenance ratio, forced selling is triggered, and the resulting supply of shares can accelerate the decline further, potentially creating a vicious cycle in which margin positions taken at successively lower price levels are liquidated one after another. In such a case, retail investors' losses can spill over into higher volatility for the market as a whole, so caution is needed.
Leveraged ETFs also require caution, as they can enlarge retail investors' losses and increase market volatility. Because leveraged ETFs track ±2 times the return of an underlying index, losses double if the index moves in the opposite direction from the investor's position. On top of this come losses caused by negative compounding. If an index rises 20% and then falls 20%, the loss based on the index is only 4%; but a 2x leveraged ETF rises 40% and then falls 40%, so the loss widens to 16%. Leveraged ETFs also charge higher management fees than ordinary ETFs and show larger tracking errors and price–NAV divergences, so investors may bear additional costs unrelated to the return of the underlying index. Furthermore, the hedging process of leveraged ETFs creates demand to trade ±2 times the underlying index, which can increase the index's volatility.4) In particular, when the index rises or falls sharply, sizeable hedging volumes have to be bought or sold near the market close, which may add further to the index's volatility.5)
High-multiple leveraged products such as unsettled-payment trading, CFDs, and futures and options carry an even greater risk of loss than margin loans or leveraged ETFs. This is because these products not only have high leverage multiples but also leave very little time before losses are locked in. In unsettled-payment trading, the purchase amount must be paid within two business days, the settlement date; if it is not paid, forced selling is executed on the next business day, so the investor has virtually no room to wait for the price to recover. CFDs and futures and options trading require daily mark-to-market settlement to maintain the margin level, so if the margin falls below the maintenance level the investor is immediately asked to deposit more, and forced liquidation follows if they cannot do so. In particular, when stock prices fall sharply, forced selling from these products tends to be concentrated, which in turn causes further price declines and can spread into greater volatility across the entire stock market.
Medium- to Long-Term Tasks to Curb Overheating in Leveraged Products
To minimize the side effects of overheated investment in leveraged products — including the higher risk of losses for retail investors and the possibility of greater stock market volatility — this article proposes measures to strengthen investor protection, improve financial stability, and broaden the base of long-term institutional investors.
First, in order to curb indiscriminate leveraged investment by retail investors, it is necessary to consider tightening entry rules for high-risk leveraged products. Financial companies should be encouraged to observe the appropriateness principle strictly, so that disclosure of risks is strengthened for retail investors with a low capacity to absorb losses and so that firms refrain from marketing and other forms of investment solicitation for leveraged products. It is also worth considering a system that identifies, on a semi-annual or annual basis, accounts that have accumulated losses from leveraged investment, strengthens risk disclosure for them, and keeps the share of leveraged investment within a certain proportion of total investment assets. From this perspective, the financial authorities' recent decision to pursue a total-volume management scheme that limits each individual's investment in single-stock leveraged ETFs to within 20% of their total investment amount is a positive step. However, if relatively strict rules are applied only to particular products, a balloon effect may occur in which demand shifts to other leveraged products at home and abroad. Over the medium to long term, it would therefore be desirable to build a consistent regulatory framework covering all leveraged products.
Second, to improve financial stability, close monitoring is needed so that the size of leveraged products does not become excessive. Specifically, where there is a possibility of greater instability in financial markets, authorities could look for ways to keep the margin loan balance and the total net assets of leveraged ETFs within certain levels. This is because, if forced liquidations occur when margin loans have grown excessively large, price declines accelerate, and those declines in turn trigger more forced selling, acting as a catalyst for greater volatility. Likewise, if leveraged ETFs grow too large and the underlying index falls sharply, large hedging volumes released near the close may increase price volatility. In this regard, the financial authorities' move to introduce emergency powers — such as lowering leverage multiples when markets swing sharply — by drawing on the reform case of Hong Kong's Securities and Futures Commission is expected to contribute to greater financial market stability.6)
Third, institutional improvements are needed to build a culture of long-term investment among retail investors. Since the expansion of leveraged investment is closely linked to trading practices centered on short-term buying and selling, a fundamental solution requires an institutional foundation that encourages long-term, diversified investment. To this end, it is necessary to improve the competitiveness of public funds and to reform the retirement pension and ISA systems in order to expand the market participation of domestic long-term institutional investors. Drawing on Japan's example of raising the annual contribution limit for NISA and extending the tax-free period indefinitely, Korea should consider substantially expanding the tax benefits of the ISA and personal pension systems. In addition, a structure in which tax benefits grow the longer shares are held would help reduce incentives for short-term trading and encourage long-term holding. Introducing a fund-type structure for retirement pensions and improving the substance of the default option are also important tasks, as they would widen the channels through which long-term money flows steadily into the capital market. Finally, financial education should be strengthened across the entire life cycle — from adolescence through middle age and old age — to make people aware of the risks of short-term leveraged investment and to encourage them to invest a portion of their surplus funds in a diversified way over long periods, thereby supporting individuals' asset building.
1) Between July 1, 2025 and June 30, 2026, the KOSPI rose 176%, while returns were 107% for Taiwan’s TAIEX, 73% for Japan’s Nikkei, 29% for the U.S. NASDAQ, 20% for the UK’s FTSE, and 19% for China’s Shanghai Composite.
2) See https://www.finra.org/rules-guidance/key-topics/margin-accounts/margin-statistics
3) See Jang (2026)
4) See Jang (2026)
5) See Jang (2026)
6) See https://apps.sfc.hk/edistributionWeb/gateway/EN/news-and-announcements/news/doc?refNo=26PR115
References
Jang, Keunhyeok, 2026, Stock Market Trends Before and After the Launch of Single-Stock Leveraged and Inverse ETFs and Their Implications, Capital Market Focus No. 2026-13.