Our bi-weekly Opinion provides you with latest updates and analysis on major capital market and financial investment industry issues.
Shortening the Settlement Cycle in the US Stock Market and Relevant Responses
Publication date Dec. 19, 2023
Summary
Currently, securities transactions in major economies, including Korea, settle within two business days after the trade date. This settlement cycle reduces the actual trading volume through netting, thereby enhancing trading efficiency and mitigating settlement risks. However, if one party involved in a stock transaction undergoes a deterioration in financial conditions or sudden stock price fluctuations, it could lead to the failure to fulfill trade obligations, exposing the other party to credit risk. This problem can be effectively addressed by adopting a shortened settlement cycle.
Having witnessed heightened stock market volatility during the pandemic, the US securities industry and retail investors called for shortening the settlement cycle to reduce margin requirement. In response, the US announced that the settlement cycle would be shortened to T+1 starting from May 28, 2024. Canada and Mexico also unveiled their plan to reduce the settlement cycle in the same week, given their close ties to the US securities market and numerous cross-listed securities. According to the US Depository Trust and Clearing Corporation (DTCC), the transition to the T+1 settlement period is anticipated to cut margin requirements for mitigating settlement risk by 41%.
In a survey conducted about nine months prior to the shortened settlement cycle introduction in the US, the securities industry is found to have not yet completed preparations to accommodate the impending shortened settlement cycle. The survey, which targets the global securities industry, reveals that only 40% of respondents—investors or custodians—expressed confidence in completing system tests for the shortened settlement cycle before the scheduled implementation in May 2024. It is also notable that the securities industry in North America has made significant strides in readiness for the shortened settlement cycle, while preparations in Europe and Asia are still in their nascent stages. India, which adopted the T+1 settlement cycle in January 2023, operates its market stably. However, the smooth operation is largely attributed to substantial costs incurred by the securities market participants.
To adapt to the T+1 settlement cycle in the US, Korean securities firms may need to implement measures such as extended office hours and switch to different overseas brokerage firms. The dates for dividend payment and the transfer of rights also change following the new settlement cycle, thereby affecting retail investors. In the initial stages of the T+1 settlement cycle, there could be a temporary increase in settlement failures. Furthermore, given that trading in the US continues even during events like reverse stock splits, there may be confusion in executing the transfer of rights.
Having witnessed heightened stock market volatility during the pandemic, the US securities industry and retail investors called for shortening the settlement cycle to reduce margin requirement. In response, the US announced that the settlement cycle would be shortened to T+1 starting from May 28, 2024. Canada and Mexico also unveiled their plan to reduce the settlement cycle in the same week, given their close ties to the US securities market and numerous cross-listed securities. According to the US Depository Trust and Clearing Corporation (DTCC), the transition to the T+1 settlement period is anticipated to cut margin requirements for mitigating settlement risk by 41%.
In a survey conducted about nine months prior to the shortened settlement cycle introduction in the US, the securities industry is found to have not yet completed preparations to accommodate the impending shortened settlement cycle. The survey, which targets the global securities industry, reveals that only 40% of respondents—investors or custodians—expressed confidence in completing system tests for the shortened settlement cycle before the scheduled implementation in May 2024. It is also notable that the securities industry in North America has made significant strides in readiness for the shortened settlement cycle, while preparations in Europe and Asia are still in their nascent stages. India, which adopted the T+1 settlement cycle in January 2023, operates its market stably. However, the smooth operation is largely attributed to substantial costs incurred by the securities market participants.
To adapt to the T+1 settlement cycle in the US, Korean securities firms may need to implement measures such as extended office hours and switch to different overseas brokerage firms. The dates for dividend payment and the transfer of rights also change following the new settlement cycle, thereby affecting retail investors. In the initial stages of the T+1 settlement cycle, there could be a temporary increase in settlement failures. Furthermore, given that trading in the US continues even during events like reverse stock splits, there may be confusion in executing the transfer of rights.
Novice retail investors often find themselves perplexed when attempting to cash out stocks, only to discover that the funds from the stock sale are not immediately available for withdrawal. In Korea, stock transactions are processed based on the T+2 timeline. Simply put, if one enters into a stock sale contract today, the exchange of stock and funds actually takes place on the third trading day. Similarly, when a stock purchase contract is signed, the actual payment and transfer of ownership are executed on the third trading day. It means that the proceeds from a stock sale are available for withdrawal two days after the stock transaction. In a similar manner, when paying only the margin for purchasing a stock, the investor must make the full payment within two trading days to acquire the stock.
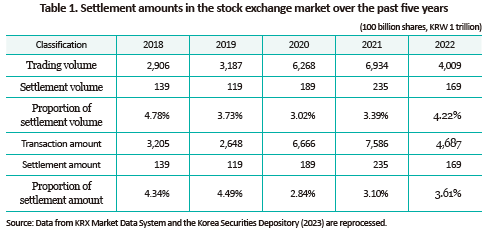
Why does the stock trading adopt the T+2 settlement process instead of an real-time settlement? As of October 2023, the average daily trading volume in the Korean stock market stands at 1.4 billion shares, with a transaction value of KRW 15 trillion. This figure represents 23.22 times the size of listed stocks and 12.4 times the market capitalization in the Korean stock market. If each transaction were settled in real-time, it would entail transferring securities and funds equivalent to multiples of the listed stocks and market capitalization in a matter of seconds. This process would be highly inefficient given transaction costs. On the other hand, by pushing back settlement, brokerage firms can curtail unnecessary movement of securities and funds through netting. In the settlement process of the Korean stock exchange market, securities brokerages participate as members and the daily trading data of each brokerage's clients are consolidated to determine the positions of each stock. The direction and amount of funds and securities movements are determined based on final positions. As of 2022, the total annual trading volume stands at 40.09 billion shares., but 1.69 billion shares which account for only 4.22% of the total trading volume are settled after netting. In terms of money, most of the total value worth KRW 468.7 trillion is netted, with the actual settled value of KRW 169 trillion accounting for 3.61% of the total. In the past, the real-time settlement was technically impossible. Even with technical advancements today, the efficiency of trading through the settlement cycle and netting is evident. Notably, institutional stock settlement involving trust companies and custodians takes a substantial amount of time. This is especially true for foreign investors, as they prepare Korean won after the transaction is confirmed. Due to the time zone differences between offices, it takes a considerable amount of time in trade confirmation and settlement instructions, which delays the final settlement.
However, extending the settlement cycle increases exposure to risk in proportion. Until the settlement is made after trade execution, one party responsible for clearing and settlement may experience a deterioration in financial conditions or a sudden fluctuation in securities prices, preventing the party from executing the settlement as planned. Furthermore, the settlement failure of an individual participant may affect other participants, potentially triggering a series of settlement failures across the entire market. Settlement risk increases in proportion to the duration from trade execution to settlement and thus, it can be mitigated by shortening the settlement cycle. To manage settlement risk, each securities exchange asks market participants to deposit margin for unsettled positions and adopt settlement risk managing programs such as deferred net settlement (DNS) and buy-in process1) to prevent the spread of settlement risk.
The US move to the T+1 settlement cycle
Currently, major economies including the US, the UK, Japan, Singapore as well as Korea adopt the T+2 settlement cycle for stock markets. However, the US, which represents 42% of the global stock market, has recently decided to shorten the stock market settlement cycle to T+1.2) This change stems from the rapid increase in volatility in meme stocks, especially GameStop. The explosive trading of meme stocks by retail investors led to a surge in the trading volume and price volatility of these stocks, resulting in a proportional increase in margin requirements. Brokerages like Robinhood suspended the purchase of those meme stocks as it became unable to meet the margin requirements. This decision sparked intense backlash from retail investors, leading to several class-action suits filed against the brokerages.3) In the aftermath of this incident, the securities industry has called for shortening settlement cycle to alleviate the burden of margin requirements and reduce settlement risk. Retail investors, who have experienced real-time settlements from virtual asset trading, also advocate for a shortened settlement cycle for swift fund withdrawals.
In response, the US Depository Trust and Clearing Corporation (DTCC) published a white paper highlighting the need for a shorter settlement cycle in 2021, suggesting that the reduction in the settlement cycle could cut margin requirements by nearly 41%.4) In February 2022, the US Securities and Exchange Commission (SEC) announced an amendment to the settlement cycle system, including a change of the securities standard settlement cycle to T+1.5) The amendment requires institutional investors to devise the procedures for swift trade confirmation while obligating central matching service providers (CMSPs) to adopt the automated straight-through process (STP). The SEC initially mentioned that it would reduce the settlement cycle starting from March 1, 2024, but it later changed the official implementation date to May 28, 2024 after consulting with the market participants and Canada. Following in the US footsteps, Canada and Mexico also announced a shortening of the settlement cycle to T+1 commencing on May 27, 2024, given their close ties to the US securities market and numerous cross-listed securities.6)
Readiness for implementation of a shortened settlement cycle
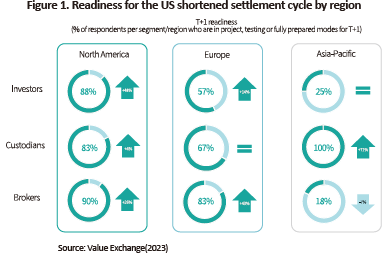
The current settlement process based on T+2 must be reduced to implement a shorter settlement cycle. For the securities industry, the shortened settlement cycle must act as a huge obstacle, particularly to foreign investors affected by time zone differences. According to a survey covering the global securities industry on the readiness for the US T+1 settlement cycle, only 73% of respondents indicated that they were making preparations for the transition to T+1, as of September 2023. In the survey, North America ranked first in terms of readiness for T+1 settlement cycle, followed by Europe and the Asia-Pacific region.7) Specifically, it is reported that personnel expansion and system automation to accommodate a shortened settlement cycle are already underway, while fund procurement, foreign exchange and securities lending (recall booking) are still underprepared. It should be noted that among the surveyed investors and custodians, only 40% mentioned plans to complete testing for the T+1 settlement cycle before May 2024. This heralds market confusion and an increase in settlement failures in the early phases of the T+1 settlement cycle.
India’s experience with the T+1 settlement cycle
The transition to a T+1 settlement cycle is not entirely new to investors. India initiated discussions on shortening the settlement cycle in September 2021, and transitioned to T+1 for the bottom 100 securities in terms of the average daily trading volume in February 2022. Since January 27, 2023, it has adopted the T+1 settlement cycle to all listed companies stock trading. In the transition process, industry participants including the Asia Securities Industry & Financial Markets Association (ASIFMA) highlighted practical challenges, and Financial Times Stock Exchange (FTSE) Russell also expressed concerns that foreign investors could be forced into pre-funding.8)9) Despite these concerns, the shortened settlement cycle has been stably implemented, thanks to a proactive response from India’s financial authorities and concerted efforts within the industry. There was no notable increase in settlement failures and the foreign investments into the Indian market remained high.10) It is noteworthy that the successful implementation was much indebted to considerable expenditures of the securities industry, including the adoption of three-shift working schedules and pre-funding. Additionally, it is necessary to take into account the Indian market’s potential for delivering high returns, making it an attractive market for foreign investors even with high costs arising from the shortened settlement cycle. However, it is doubtful that the global investment industry will incur costs and make investments for markets with lower expected returns if they move to the T+1 settlement cycle.
The impact of the US T+1 settlement cycle on retail investors
As of the end of the third quarter of 2023, the US securities managed by the Korea Securities Depository amount to around KRW 82.5 trillion. Consequently, the shortened settlement cycle in the US is anticipated to have a significant impact on Korean investors.11) Korean securities brokerages handle settlement for US securities based on the T+3 timeline due to the time zone difference with the US, but the settlement process should be streamlined to T+2 starting from May next year. In response to this transition, they may need to operate night offices and switch to different overseas brokers.
The shortened settlement cycle will allow retail investors to cash out their US securities by one day earlier. On top of that, the transfer date of various rights, including dividend entitlement, will change accordingly. Under the T+2 settlement cycle, investors are registered in the shareholder registry two days after the stock purchase. To become eligible for dividends, they should purchase stocks at least two days before the ex-dividend date. With the transition to the T+1 settlement cycle, they need to purchase stocks up to one day before the ex-dividend date to receive dividends. The ex-dividend date will be adjusted in sync with the dividend record date.
In the initial stages, the system tailored to the shortened settlement cycle may not be fully established, possibly leading to a short-term increase in settlement failures. In the US stock market, the settlement failure rate stood at 8.6% in the first half of 2020 and 7.4% in the second half, quite high levels considering that no settlement default was reported in the Korean stock market in 2022. If global custodians and brokerages remain underprepared in the early stages of the shortened settlement cycle, settlement failures could increase further. Furthermore, considering that trading in the US continues even during events like reverse stock splits, there may be confusion in executing the transfer of rights if brokerage systems are not prepared for such events.
1) Deferred net settlement (DNS) is a system in which if securities are not paid by the settlement deadline due to factors like liquidity shortages, an equivalent amount of cash is paid and the securities settlement is deferred to the next settlement date. If the non-payment of settlement securities persists even after the deferred settlement date or if the securities are expected to remain unpaid as of the record date due to corporate events (dividends, increase and reduction of capital, stock splits, mergers, etc.), the mechanism called “buy-in” can be implemented. In the process, the exchange directly purchases the securities under the name of the settlement member and delivers them to the counterparty.
2) Reuters, February 8, 2023, Outsized U.S. share of world equity may revert to norm.
3) CNN, January 29, 2021, Reddit investors shake up Wall Street.
4) DTCC, February 2021, Advancing together: Leading the industry to accelerated settlement, White paper.
5) SEC, February 9, 2022, SEC issues proposal to reduce risks in clearance and settlement.
6) As May 27, 2024 falls on Memorial Day, a US public holiday, the shortened settlement cycle will commence the following day, on May 28.
7) The survey was conducted by the Canadian consulting firm, The Value Exchange, in collaboration with DTCC, TMX, AFME, ASIFMA, EFAMA, and ISITC. A total of 306 global experts responded to the survey.
8) ASIFMA, September 30, 2021, Open letter to securities and exchange board of India from foreign portfolio investors (FPIs) on T+1 Settlement, Press Release.
FTSE Russell, September 29, 2022, FTSE equity country Classification September 2022 annual announcement.
9) Foreign investors generally execute currency exchange after confirming the trade. However, if the shortened settlement cycle does not give sufficient time for currency exchange, they may opt to engage in securities transactions after currency exchange.
10) FTSE Russell, March 30, 2023, FTSE equity country classification interim announcement.
11) Newsis, November 14, 2023, “Retail investors invest KRW 82.5 trillion…Korea Securities Depository cautions on the US system including payment delays”.
Why does the stock trading adopt the T+2 settlement process instead of an real-time settlement? As of October 2023, the average daily trading volume in the Korean stock market stands at 1.4 billion shares, with a transaction value of KRW 15 trillion. This figure represents 23.22 times the size of listed stocks and 12.4 times the market capitalization in the Korean stock market. If each transaction were settled in real-time, it would entail transferring securities and funds equivalent to multiples of the listed stocks and market capitalization in a matter of seconds. This process would be highly inefficient given transaction costs. On the other hand, by pushing back settlement, brokerage firms can curtail unnecessary movement of securities and funds through netting. In the settlement process of the Korean stock exchange market, securities brokerages participate as members and the daily trading data of each brokerage's clients are consolidated to determine the positions of each stock. The direction and amount of funds and securities movements are determined based on final positions. As of 2022, the total annual trading volume stands at 40.09 billion shares., but 1.69 billion shares which account for only 4.22% of the total trading volume are settled after netting. In terms of money, most of the total value worth KRW 468.7 trillion is netted, with the actual settled value of KRW 169 trillion accounting for 3.61% of the total. In the past, the real-time settlement was technically impossible. Even with technical advancements today, the efficiency of trading through the settlement cycle and netting is evident. Notably, institutional stock settlement involving trust companies and custodians takes a substantial amount of time. This is especially true for foreign investors, as they prepare Korean won after the transaction is confirmed. Due to the time zone differences between offices, it takes a considerable amount of time in trade confirmation and settlement instructions, which delays the final settlement.
The US move to the T+1 settlement cycle
Currently, major economies including the US, the UK, Japan, Singapore as well as Korea adopt the T+2 settlement cycle for stock markets. However, the US, which represents 42% of the global stock market, has recently decided to shorten the stock market settlement cycle to T+1.2) This change stems from the rapid increase in volatility in meme stocks, especially GameStop. The explosive trading of meme stocks by retail investors led to a surge in the trading volume and price volatility of these stocks, resulting in a proportional increase in margin requirements. Brokerages like Robinhood suspended the purchase of those meme stocks as it became unable to meet the margin requirements. This decision sparked intense backlash from retail investors, leading to several class-action suits filed against the brokerages.3) In the aftermath of this incident, the securities industry has called for shortening settlement cycle to alleviate the burden of margin requirements and reduce settlement risk. Retail investors, who have experienced real-time settlements from virtual asset trading, also advocate for a shortened settlement cycle for swift fund withdrawals.
In response, the US Depository Trust and Clearing Corporation (DTCC) published a white paper highlighting the need for a shorter settlement cycle in 2021, suggesting that the reduction in the settlement cycle could cut margin requirements by nearly 41%.4) In February 2022, the US Securities and Exchange Commission (SEC) announced an amendment to the settlement cycle system, including a change of the securities standard settlement cycle to T+1.5) The amendment requires institutional investors to devise the procedures for swift trade confirmation while obligating central matching service providers (CMSPs) to adopt the automated straight-through process (STP). The SEC initially mentioned that it would reduce the settlement cycle starting from March 1, 2024, but it later changed the official implementation date to May 28, 2024 after consulting with the market participants and Canada. Following in the US footsteps, Canada and Mexico also announced a shortening of the settlement cycle to T+1 commencing on May 27, 2024, given their close ties to the US securities market and numerous cross-listed securities.6)
Readiness for implementation of a shortened settlement cycle
The current settlement process based on T+2 must be reduced to implement a shorter settlement cycle. For the securities industry, the shortened settlement cycle must act as a huge obstacle, particularly to foreign investors affected by time zone differences. According to a survey covering the global securities industry on the readiness for the US T+1 settlement cycle, only 73% of respondents indicated that they were making preparations for the transition to T+1, as of September 2023. In the survey, North America ranked first in terms of readiness for T+1 settlement cycle, followed by Europe and the Asia-Pacific region.7) Specifically, it is reported that personnel expansion and system automation to accommodate a shortened settlement cycle are already underway, while fund procurement, foreign exchange and securities lending (recall booking) are still underprepared. It should be noted that among the surveyed investors and custodians, only 40% mentioned plans to complete testing for the T+1 settlement cycle before May 2024. This heralds market confusion and an increase in settlement failures in the early phases of the T+1 settlement cycle.
The transition to a T+1 settlement cycle is not entirely new to investors. India initiated discussions on shortening the settlement cycle in September 2021, and transitioned to T+1 for the bottom 100 securities in terms of the average daily trading volume in February 2022. Since January 27, 2023, it has adopted the T+1 settlement cycle to all listed companies stock trading. In the transition process, industry participants including the Asia Securities Industry & Financial Markets Association (ASIFMA) highlighted practical challenges, and Financial Times Stock Exchange (FTSE) Russell also expressed concerns that foreign investors could be forced into pre-funding.8)9) Despite these concerns, the shortened settlement cycle has been stably implemented, thanks to a proactive response from India’s financial authorities and concerted efforts within the industry. There was no notable increase in settlement failures and the foreign investments into the Indian market remained high.10) It is noteworthy that the successful implementation was much indebted to considerable expenditures of the securities industry, including the adoption of three-shift working schedules and pre-funding. Additionally, it is necessary to take into account the Indian market’s potential for delivering high returns, making it an attractive market for foreign investors even with high costs arising from the shortened settlement cycle. However, it is doubtful that the global investment industry will incur costs and make investments for markets with lower expected returns if they move to the T+1 settlement cycle.
The impact of the US T+1 settlement cycle on retail investors
As of the end of the third quarter of 2023, the US securities managed by the Korea Securities Depository amount to around KRW 82.5 trillion. Consequently, the shortened settlement cycle in the US is anticipated to have a significant impact on Korean investors.11) Korean securities brokerages handle settlement for US securities based on the T+3 timeline due to the time zone difference with the US, but the settlement process should be streamlined to T+2 starting from May next year. In response to this transition, they may need to operate night offices and switch to different overseas brokers.
The shortened settlement cycle will allow retail investors to cash out their US securities by one day earlier. On top of that, the transfer date of various rights, including dividend entitlement, will change accordingly. Under the T+2 settlement cycle, investors are registered in the shareholder registry two days after the stock purchase. To become eligible for dividends, they should purchase stocks at least two days before the ex-dividend date. With the transition to the T+1 settlement cycle, they need to purchase stocks up to one day before the ex-dividend date to receive dividends. The ex-dividend date will be adjusted in sync with the dividend record date.
In the initial stages, the system tailored to the shortened settlement cycle may not be fully established, possibly leading to a short-term increase in settlement failures. In the US stock market, the settlement failure rate stood at 8.6% in the first half of 2020 and 7.4% in the second half, quite high levels considering that no settlement default was reported in the Korean stock market in 2022. If global custodians and brokerages remain underprepared in the early stages of the shortened settlement cycle, settlement failures could increase further. Furthermore, considering that trading in the US continues even during events like reverse stock splits, there may be confusion in executing the transfer of rights if brokerage systems are not prepared for such events.
1) Deferred net settlement (DNS) is a system in which if securities are not paid by the settlement deadline due to factors like liquidity shortages, an equivalent amount of cash is paid and the securities settlement is deferred to the next settlement date. If the non-payment of settlement securities persists even after the deferred settlement date or if the securities are expected to remain unpaid as of the record date due to corporate events (dividends, increase and reduction of capital, stock splits, mergers, etc.), the mechanism called “buy-in” can be implemented. In the process, the exchange directly purchases the securities under the name of the settlement member and delivers them to the counterparty.
2) Reuters, February 8, 2023, Outsized U.S. share of world equity may revert to norm.
3) CNN, January 29, 2021, Reddit investors shake up Wall Street.
4) DTCC, February 2021, Advancing together: Leading the industry to accelerated settlement, White paper.
5) SEC, February 9, 2022, SEC issues proposal to reduce risks in clearance and settlement.
6) As May 27, 2024 falls on Memorial Day, a US public holiday, the shortened settlement cycle will commence the following day, on May 28.
7) The survey was conducted by the Canadian consulting firm, The Value Exchange, in collaboration with DTCC, TMX, AFME, ASIFMA, EFAMA, and ISITC. A total of 306 global experts responded to the survey.
8) ASIFMA, September 30, 2021, Open letter to securities and exchange board of India from foreign portfolio investors (FPIs) on T+1 Settlement, Press Release.
FTSE Russell, September 29, 2022, FTSE equity country Classification September 2022 annual announcement.
9) Foreign investors generally execute currency exchange after confirming the trade. However, if the shortened settlement cycle does not give sufficient time for currency exchange, they may opt to engage in securities transactions after currency exchange.
10) FTSE Russell, March 30, 2023, FTSE equity country classification interim announcement.
11) Newsis, November 14, 2023, “Retail investors invest KRW 82.5 trillion…Korea Securities Depository cautions on the US system including payment delays”.