Our bi-weekly Opinion provides you with latest updates and analysis on major capital market and financial investment industry issues.

An Analysis of Competitive Fee Reductions in Korea’s ETF Market
Publication date Jun. 10, 2025
Summary
Korean asset management companies have recently engaged in aggressive fee-cutting competition, particularly in ETFs tracking major US indices. This development reflects a strategic response to multiple factors, such as strong first-mover advantages in the ETF market, surging investor demand, and intensifying competition from US-listed ETFs. While this competition benefits investors by providing access to ETF exposure at historically low costs, it has also raised concerns over unsustainable price competition and potential erosion of industry-wide profitability. Analysis results indicate that the fee-cutting race in the Korean ETF market remains largely confined to broad-based index ETFs, whose contribution to total fee income has declined significantly over time. As a result, the recent wave of fee reductions appears to have only a limited impact on the profitability of Korea’s ETF industry. Meanwhile, the rapid growth of thematic ETFs, most of which continue to charge significantly higher fees, has helped alleviate concerns about shrinking margins across the sector. While investors can take advantage of low-cost ETFs, they must also recognize the potential risks associated with thematic ETFs. In light of these dynamics, regulatory authorities should focus on enhancing market integrity by preventing aggressive marketing activities and curbing unfair trading practices in the thematic ETF segment.
The recent escalation of fee-cutting competition among Korean asset management companies has drawn significant attention in the domestic exchange-traded fund (ETF) market. This trend was catalyzed on February 6, 2025, when the total expense ratio for the TIGER S&P 500 and NASDAQ 100 ETFs was reduced to 0.68 basis points (bp), one-tenth of the previous level. The following day, the KODEX S&P 500 and NASDAQ 100 ETFs responded by lowering fees to 0.62 bp. On February 11, RISE joined the competition, cutting fees to 0.47 bp for the S&P 500 ETF and 0.62 bp for the NASDAQ 100 ETF. This escalating round of fee reductions has raised concerns over excessive price competition, particularly fears that large asset managers may erode the market position of smaller peers and undermine profitability across the industry.
As a result of this aggressive fee-cutting race, the actual cost borne by investors has declined to historically low levels. For example, an investment of KRW 100 million in these ETFs now incurs an annual fee of merely KRW 4,000 to KRW 7,000. This is strikingly low in the Korean market, where equity mutual funds typically charge around KRW 1.2 million in annual fees for the same investment amount and standard equity ETFs cost approximately KRW 250,000. Even US-listed ETFs tracking the same indices typically impose fees ranging from KRW 30,000 to KRW 200,000 under similar investment conditions, reaffirming the exceptionally low-cost structure of Korean offerings. However, major US-listed ETFs benefit from operational efficiencies and economies of scale in their home market. Their net asset size often ranges from KRW 400 trillion to KRW 900 trillion, far surpassing the KRW 1 trillion to KRW 8 trillion range typical of Korean equivalents. From the investor’s perspective, Korean ETFs tracking benchmark indices offer highly cost-efficient exposure, even by global standards. From the perspective of asset management companies, however, these ultra-low fee levels inevitably pose serious concerns over the long-term profitability and sustainability of their ETF products.
Drivers of fee competition
There are key factors behind the aggressive price competition observed among ETFs tracking the S&P 500 and NASDAQ 100 indices. The first factor is the strong first-mover advantage prevalent in the ETF market. Asset management companies, informed by past market experience, recognize that early entry often translates into long-term dominance. A case in point is KODEX 200, Korea’s first ETF launched in 2002, which has maintained its leading position in net assets for nearly two decades. Notably, among the 14 ETFs tracking the KOSPI 200 index, KODEX 200 currently imposes the second-highest total expense ratio (15 bp), nearly nine times higher than that of the lowest-cost competitor (1.7 bp), yet it continues to command the largest share of net assets in the category.
Similar patterns are observed in the US market. The SPDR S&P 500 ETF (SPY), the first ETF listed in the US in 1993, has retained its position as the world’s largest ETF for nearly three decades. Although briefly overtaken by SPDR Gold Shares (GLD) during the 2011 gold rally and more recently by the Vanguard S&P 500 ETF (VOO) in terms of AUM, SPY continues to maintain significant scale despite charging a fee nearly three times higher than its competitors. In the NASDAQ 100 segment, the Invesco QQQ Trust (QQQ), introduced in 1999, has maintained market dominance, reflecting the enduring early-mover advantage.
In Korea, investor interest in US index-tracking ETFs has grown rapidly only in recent years, and the competitive landscape for these products remains in its early phase with no single product having secured a dominant position. Against this backdrop, the ongoing fee-cutting race can be viewed as a preemptive strategy by asset managers to capture long-term market leadership in this product category.
Another major driver of fee competition is the explosive growth in domestic investor demand for US equities. Over the past decade, the S&P 500 Total Return Index has delivered an annualized return of 13.1%. This return not only significantly outperforms the KOSPI Total Return Index’s 5.6% annualized return over the same period, but also far exceeds that of equity markets in other major economies, such as the UK, France, Canada, Australia, and Japan. Beyond this strong performance, US markets appeal to Korean investors through their presence of globally influential and widely recognized companies such as Apple, Tesla, and NVIDIA. From a long-term asset allocation perspective, the US stock market also plays a central role in global portfolios, accounting for 64% of the MSCI All Country World Index (ACWI). Given that the S&P 500 and NASDAQ 100 indices represent the primary vehicles for gaining exposure to the US stock market, ETFs tracking these indices are well-positioned to become market-defining products, allowing their issuers to secure a significant share of the broader ETF market.
A third factor of the fee-cutting trend is the growing pressure from US-listed ETFs managed by global asset management companies. As Korean investors gain significantly improved access to US markets, with trading costs and convenience now comparable to domestic stock transactions, the traditional reliance on locally managed ETFs for US stock exposure has weakened. Increasingly, investor capital is being allocated directly to US-listed stocks and ETFs, effectively bypassing domestic asset managers. This shift suggests that Korean asset managers are no longer competing solely with one another in the US equity ETF segment, but are now in direct competition with US-based ETF providers. According to the Korea Securities Depository, Korean investors collectively hold around KRW 11.3 trillion in US-listed ETFs that track the S&P 500 and NASDAQ 100. Major holdings include QQQ (KRW 3.7 trillion), VOO (KRW 2.9 trillion), SPY (KRW 2.6 trillion), QQQM (KRW 0.8 trillion), IVV (KRW 0.7 trillion), and SPLG (KRW 0.6 trillion). This figure equates to roughly 43% of KRW 26.2 trillion in total net assets held in Korea-listed ETFs tracking the same indices. Given that Korean pension accounts, which hold a substantial portion of domestic ETF assets, are restricted from investing in US-listed ETFs, it is highly plausible that, in unrestricted brokerage accounts, Korean investor exposure to US-listed ETFs already exceeds that of their domestic counterparts.
Moreover, US-listed ETFs offer greater trading liquidity and are efficiently structured for long-term investing, building on in-kind creation and redemption mechanisms. In addition, unlike Korean-listed ETFs, US-listed products may qualify for separate capital gains tax treatment, an important consideration for high-income and high-net-worth individuals seeking to lower their overall tax burden. Amid this mounting competitive pressure, Korean asset managers appear to have responded strategically by aggressively lowering fees to counter the multifaceted advantages of US-listed ETFs and attract domestic investor capital.
Segmented market structure
This section examines whether the intense fee competition observed among ETFs tracking the S&P 500 and NASDAQ 100 extends to other equity ETF segments. The figure below illustrates the distribution of fee structures across equity ETFs. Each dot represents an individual ETF, with its size proportional to the fund’s total net assets. The horizontal axis plots the Herfindahl-Hirschman Index (HHI), a measure of portfolio concentration, where lower HHI values indicate greater diversification. As expected, broad-based index ETFs tend to exhibit lower HHI values, while thematic ETFs, focused on specific sectors or trends, generally show higher concentration levels. The vertical axis reflects each ETF’s total expense ratio.
A distinct bifurcation is evident in the equity ETF market. In both domestic and US equity ETF segments, broad-based index ETFs with large net assets and low HHI values1) consistently offer low expense ratios, typically below 10 bp.2) In contrast, thematic ETFs, which exhibit higher HHI values, tend to have expense ratios in the range of 40 bp to 50 bp. This pattern suggests that fee competition is largely concentrated in a limited subset of products, while fee levels remain elevated in other segments.3)

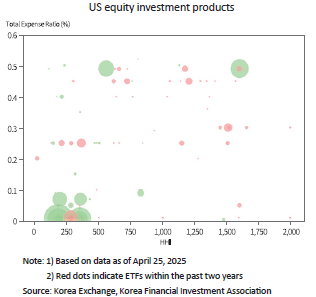
The concentration of fee competition in specific ETF segments can be attributed to the following factors. Broad market indices, such as KOSPI 200, KOSDAQ 150, S&P 500, and NASDAQ 100, are limited in number, and ETFs tracking these benchmarks offer few opportunities for meaningful product differentiation. In this environment, price emerges as the principal basis for competition. By contrast, thematic ETFs compete not only on cost but also on product concept, portfolio composition, and strategic distinctiveness. This differentiation is evident in the previously discussed figure, which shows a wide dispersion of HHI values among thematic ETFs, indicating their heterogeneous underlying assets. Accordingly, when selecting thematic ETFs, investors often prioritize factors such as the growth potential of relevant themes or product distinctiveness over expense ratios.
In the early stages of ETF market development, broad-based index ETFs dominated in terms of market share, making this segment the strategic focal point for asset managers. However, since the COVID-19 pandemic, thematic ETFs have expanded their market share and grown in importance as a revenue source. According to Kim and Kwon (2025),4) as of the end of June 2024, thematic ETFs accounted for 26% of the total market by net assets. With a net asset-weighted average expense ratio of 34.3 bp—more than five times that of index ETFs (6.5 bp)—thematic ETFs are now estimated to generate over half of all equity ETF fee income. Meanwhile, the contribution of broad-based index ETFs to total fee income has declined to 20%, underscoring a structural shift in the industry’s revenue composition.
These findings suggest that the ongoing fee competition is far from a market-wide trend. Fierce pricing competition remains largely confined to the broad-based index ETF segment, which now represents a shrinking share of overall fee income. As a result, the current wave of fee reductions in this segment is unlikely to pose a threat to the profitability of the ETF industry. Notably, the rise of thematic ETFs, where competition centers on product differentiation rather than pricing, presents market entry and growth opportunities even for mid-sized and smaller asset managers with innovative strategies. In this context, fee competition among index-tracking ETFs is expected to have only a limited adverse impact on the operating environment of smaller asset managers.
Conclusion and implications
The recent fee-cutting race among Korea’s major asset managers has been unprecedented in intensity, primarily targeting high-profile ETFs that command substantial market capital. This development has raised concerns over declining industry profitability. However, the move appears to be a strategic response to multiple factors, namely the strong first-mover advantage in the ETF market, the growth potential of index-tracking products, and intensifying direct competition from US-listed ETFs. At the same time, the rapid expansion of thematic ETFs, characterized by relatively high expense ratios, has served as a counterbalancing force, helping to mitigate the profitability impact of fee competition across the industry. In this regard, widespread fears of industry-wide margin erosion may be overstated. For investors, these fee reductions offer tangible benefits. Given the key role of S&P 500 and NASDAQ 100 ETFs in global asset allocation portfolios, long-term investors can leverage these low-fee products to reduce investment costs and enhance long-term returns.
From an investor perspective, however, a more significant concern may lie in the rapid growth of thematic ETFs. These products are inherently tied to specific issues or market trends and can attract substantial retail capital inflows in a short time. Yet, when investor interest fades or new themes gain traction, existing thematic ETFs may experience declining performance and rapid capital outflows.5) Retail investors, especially those who enter at peak valuation, may face the risk of long-term underperformance and unrecoverable losses.
While strong investor demand has undoubtedly driven the thematic ETF boom, asset managers have played an equally active role through aggressive product rollout and marketing strategies. With marketing spending on the rise, enhanced regulatory oversight is essential, particularly on easily accessible social media platforms, where advertisements may violate regulations or mislead investors with overly optimistic projections. Additionally, heightened competition increases the risk of unfair practices. Regulatory authorities should closely monitor practices, such as the use of liquidity providers to artificially inflate fund size during the launch phase.6)
1) As of April 25, 2025, the HHI for the KOSPI 200 and KOSDAQ 150 indices stood at approximately 710 and 300, respectively, while the HHI for the S&P 500 and NASDAQ 100 indices was approximately 190 and 350, respectively.
2) ETFs with low HHI values but total expense ratios exceeding 10 bp are typically those that apply additional strategies, such as covered calls or dividend weighting, to broad-based indices. However, as previously noted, KODEX 200 is a pure index-tracking ETF that charges an unusually high total expense ratio of 15 bp, making it an exception among broad-based index products.
3) The study below reports a similar pattern observed in the US ETF market.
Ben-David, I., Franzoni, F., Kim, B., Moussawi, R., 2023, Competition for attention in the ETF space, The Review of Financial Studies 36, 987–1042.
4) Kim, J.C. & Kwon, M.K., 2025. Structural Shifts in the ETF Market and their Implications. Korea Capital Market Institute Issue Paper 25-02.
5) Similar patterns in both the Korean and US markets can be found in the literature cited below.
Kim, M.K., 2022, Growth and Risk Factors of Thematic ETFs, Korea Capital Market Institute Opinion 2022-06.
Ben-David, I., Franzoni, F., Kim, B., Moussawi, R., 2023, Competition for attention in the ETF space, The Review of Financial Studies 36, 987–1042.
6) Dong-A Ilbo, Oct. 7, 2024, Exclusive: Asset Managers Criticized for Lending Client Shares at Deep Discounts.
As a result of this aggressive fee-cutting race, the actual cost borne by investors has declined to historically low levels. For example, an investment of KRW 100 million in these ETFs now incurs an annual fee of merely KRW 4,000 to KRW 7,000. This is strikingly low in the Korean market, where equity mutual funds typically charge around KRW 1.2 million in annual fees for the same investment amount and standard equity ETFs cost approximately KRW 250,000. Even US-listed ETFs tracking the same indices typically impose fees ranging from KRW 30,000 to KRW 200,000 under similar investment conditions, reaffirming the exceptionally low-cost structure of Korean offerings. However, major US-listed ETFs benefit from operational efficiencies and economies of scale in their home market. Their net asset size often ranges from KRW 400 trillion to KRW 900 trillion, far surpassing the KRW 1 trillion to KRW 8 trillion range typical of Korean equivalents. From the investor’s perspective, Korean ETFs tracking benchmark indices offer highly cost-efficient exposure, even by global standards. From the perspective of asset management companies, however, these ultra-low fee levels inevitably pose serious concerns over the long-term profitability and sustainability of their ETF products.
Drivers of fee competition
There are key factors behind the aggressive price competition observed among ETFs tracking the S&P 500 and NASDAQ 100 indices. The first factor is the strong first-mover advantage prevalent in the ETF market. Asset management companies, informed by past market experience, recognize that early entry often translates into long-term dominance. A case in point is KODEX 200, Korea’s first ETF launched in 2002, which has maintained its leading position in net assets for nearly two decades. Notably, among the 14 ETFs tracking the KOSPI 200 index, KODEX 200 currently imposes the second-highest total expense ratio (15 bp), nearly nine times higher than that of the lowest-cost competitor (1.7 bp), yet it continues to command the largest share of net assets in the category.
Similar patterns are observed in the US market. The SPDR S&P 500 ETF (SPY), the first ETF listed in the US in 1993, has retained its position as the world’s largest ETF for nearly three decades. Although briefly overtaken by SPDR Gold Shares (GLD) during the 2011 gold rally and more recently by the Vanguard S&P 500 ETF (VOO) in terms of AUM, SPY continues to maintain significant scale despite charging a fee nearly three times higher than its competitors. In the NASDAQ 100 segment, the Invesco QQQ Trust (QQQ), introduced in 1999, has maintained market dominance, reflecting the enduring early-mover advantage.
In Korea, investor interest in US index-tracking ETFs has grown rapidly only in recent years, and the competitive landscape for these products remains in its early phase with no single product having secured a dominant position. Against this backdrop, the ongoing fee-cutting race can be viewed as a preemptive strategy by asset managers to capture long-term market leadership in this product category.
Another major driver of fee competition is the explosive growth in domestic investor demand for US equities. Over the past decade, the S&P 500 Total Return Index has delivered an annualized return of 13.1%. This return not only significantly outperforms the KOSPI Total Return Index’s 5.6% annualized return over the same period, but also far exceeds that of equity markets in other major economies, such as the UK, France, Canada, Australia, and Japan. Beyond this strong performance, US markets appeal to Korean investors through their presence of globally influential and widely recognized companies such as Apple, Tesla, and NVIDIA. From a long-term asset allocation perspective, the US stock market also plays a central role in global portfolios, accounting for 64% of the MSCI All Country World Index (ACWI). Given that the S&P 500 and NASDAQ 100 indices represent the primary vehicles for gaining exposure to the US stock market, ETFs tracking these indices are well-positioned to become market-defining products, allowing their issuers to secure a significant share of the broader ETF market.
A third factor of the fee-cutting trend is the growing pressure from US-listed ETFs managed by global asset management companies. As Korean investors gain significantly improved access to US markets, with trading costs and convenience now comparable to domestic stock transactions, the traditional reliance on locally managed ETFs for US stock exposure has weakened. Increasingly, investor capital is being allocated directly to US-listed stocks and ETFs, effectively bypassing domestic asset managers. This shift suggests that Korean asset managers are no longer competing solely with one another in the US equity ETF segment, but are now in direct competition with US-based ETF providers. According to the Korea Securities Depository, Korean investors collectively hold around KRW 11.3 trillion in US-listed ETFs that track the S&P 500 and NASDAQ 100. Major holdings include QQQ (KRW 3.7 trillion), VOO (KRW 2.9 trillion), SPY (KRW 2.6 trillion), QQQM (KRW 0.8 trillion), IVV (KRW 0.7 trillion), and SPLG (KRW 0.6 trillion). This figure equates to roughly 43% of KRW 26.2 trillion in total net assets held in Korea-listed ETFs tracking the same indices. Given that Korean pension accounts, which hold a substantial portion of domestic ETF assets, are restricted from investing in US-listed ETFs, it is highly plausible that, in unrestricted brokerage accounts, Korean investor exposure to US-listed ETFs already exceeds that of their domestic counterparts.
Moreover, US-listed ETFs offer greater trading liquidity and are efficiently structured for long-term investing, building on in-kind creation and redemption mechanisms. In addition, unlike Korean-listed ETFs, US-listed products may qualify for separate capital gains tax treatment, an important consideration for high-income and high-net-worth individuals seeking to lower their overall tax burden. Amid this mounting competitive pressure, Korean asset managers appear to have responded strategically by aggressively lowering fees to counter the multifaceted advantages of US-listed ETFs and attract domestic investor capital.
Segmented market structure
This section examines whether the intense fee competition observed among ETFs tracking the S&P 500 and NASDAQ 100 extends to other equity ETF segments. The figure below illustrates the distribution of fee structures across equity ETFs. Each dot represents an individual ETF, with its size proportional to the fund’s total net assets. The horizontal axis plots the Herfindahl-Hirschman Index (HHI), a measure of portfolio concentration, where lower HHI values indicate greater diversification. As expected, broad-based index ETFs tend to exhibit lower HHI values, while thematic ETFs, focused on specific sectors or trends, generally show higher concentration levels. The vertical axis reflects each ETF’s total expense ratio.
A distinct bifurcation is evident in the equity ETF market. In both domestic and US equity ETF segments, broad-based index ETFs with large net assets and low HHI values1) consistently offer low expense ratios, typically below 10 bp.2) In contrast, thematic ETFs, which exhibit higher HHI values, tend to have expense ratios in the range of 40 bp to 50 bp. This pattern suggests that fee competition is largely concentrated in a limited subset of products, while fee levels remain elevated in other segments.3)
The concentration of fee competition in specific ETF segments can be attributed to the following factors. Broad market indices, such as KOSPI 200, KOSDAQ 150, S&P 500, and NASDAQ 100, are limited in number, and ETFs tracking these benchmarks offer few opportunities for meaningful product differentiation. In this environment, price emerges as the principal basis for competition. By contrast, thematic ETFs compete not only on cost but also on product concept, portfolio composition, and strategic distinctiveness. This differentiation is evident in the previously discussed figure, which shows a wide dispersion of HHI values among thematic ETFs, indicating their heterogeneous underlying assets. Accordingly, when selecting thematic ETFs, investors often prioritize factors such as the growth potential of relevant themes or product distinctiveness over expense ratios.
In the early stages of ETF market development, broad-based index ETFs dominated in terms of market share, making this segment the strategic focal point for asset managers. However, since the COVID-19 pandemic, thematic ETFs have expanded their market share and grown in importance as a revenue source. According to Kim and Kwon (2025),4) as of the end of June 2024, thematic ETFs accounted for 26% of the total market by net assets. With a net asset-weighted average expense ratio of 34.3 bp—more than five times that of index ETFs (6.5 bp)—thematic ETFs are now estimated to generate over half of all equity ETF fee income. Meanwhile, the contribution of broad-based index ETFs to total fee income has declined to 20%, underscoring a structural shift in the industry’s revenue composition.
These findings suggest that the ongoing fee competition is far from a market-wide trend. Fierce pricing competition remains largely confined to the broad-based index ETF segment, which now represents a shrinking share of overall fee income. As a result, the current wave of fee reductions in this segment is unlikely to pose a threat to the profitability of the ETF industry. Notably, the rise of thematic ETFs, where competition centers on product differentiation rather than pricing, presents market entry and growth opportunities even for mid-sized and smaller asset managers with innovative strategies. In this context, fee competition among index-tracking ETFs is expected to have only a limited adverse impact on the operating environment of smaller asset managers.
Conclusion and implications
The recent fee-cutting race among Korea’s major asset managers has been unprecedented in intensity, primarily targeting high-profile ETFs that command substantial market capital. This development has raised concerns over declining industry profitability. However, the move appears to be a strategic response to multiple factors, namely the strong first-mover advantage in the ETF market, the growth potential of index-tracking products, and intensifying direct competition from US-listed ETFs. At the same time, the rapid expansion of thematic ETFs, characterized by relatively high expense ratios, has served as a counterbalancing force, helping to mitigate the profitability impact of fee competition across the industry. In this regard, widespread fears of industry-wide margin erosion may be overstated. For investors, these fee reductions offer tangible benefits. Given the key role of S&P 500 and NASDAQ 100 ETFs in global asset allocation portfolios, long-term investors can leverage these low-fee products to reduce investment costs and enhance long-term returns.
From an investor perspective, however, a more significant concern may lie in the rapid growth of thematic ETFs. These products are inherently tied to specific issues or market trends and can attract substantial retail capital inflows in a short time. Yet, when investor interest fades or new themes gain traction, existing thematic ETFs may experience declining performance and rapid capital outflows.5) Retail investors, especially those who enter at peak valuation, may face the risk of long-term underperformance and unrecoverable losses.
While strong investor demand has undoubtedly driven the thematic ETF boom, asset managers have played an equally active role through aggressive product rollout and marketing strategies. With marketing spending on the rise, enhanced regulatory oversight is essential, particularly on easily accessible social media platforms, where advertisements may violate regulations or mislead investors with overly optimistic projections. Additionally, heightened competition increases the risk of unfair practices. Regulatory authorities should closely monitor practices, such as the use of liquidity providers to artificially inflate fund size during the launch phase.6)
1) As of April 25, 2025, the HHI for the KOSPI 200 and KOSDAQ 150 indices stood at approximately 710 and 300, respectively, while the HHI for the S&P 500 and NASDAQ 100 indices was approximately 190 and 350, respectively.
2) ETFs with low HHI values but total expense ratios exceeding 10 bp are typically those that apply additional strategies, such as covered calls or dividend weighting, to broad-based indices. However, as previously noted, KODEX 200 is a pure index-tracking ETF that charges an unusually high total expense ratio of 15 bp, making it an exception among broad-based index products.
3) The study below reports a similar pattern observed in the US ETF market.
Ben-David, I., Franzoni, F., Kim, B., Moussawi, R., 2023, Competition for attention in the ETF space, The Review of Financial Studies 36, 987–1042.
4) Kim, J.C. & Kwon, M.K., 2025. Structural Shifts in the ETF Market and their Implications. Korea Capital Market Institute Issue Paper 25-02.
5) Similar patterns in both the Korean and US markets can be found in the literature cited below.
Kim, M.K., 2022, Growth and Risk Factors of Thematic ETFs, Korea Capital Market Institute Opinion 2022-06.
Ben-David, I., Franzoni, F., Kim, B., Moussawi, R., 2023, Competition for attention in the ETF space, The Review of Financial Studies 36, 987–1042.
6) Dong-A Ilbo, Oct. 7, 2024, Exclusive: Asset Managers Criticized for Lending Client Shares at Deep Discounts.