Our bi-weekly Opinion provides you with latest updates and analysis on major capital market and financial investment industry issues.
Kosdaq Market Development and the Role of Small- and Mid-Sized Securities Firms: Implications from U.S. Small- and Mid-Sized Investment Bank Cases
Publication date May. 19, 2026
Summary
For the Financial Services Commission's recently announced "KOSDAQ Market Trust + Innovation Enhancement Plan" to yield substantive outcomes, the market's intermediation function—which properly values KOSDAQ-listed companies and channels that valuation into long-term investment—must be complementarily strengthened. The key players in this regard are small- and mid-sized securities firms, whose research capabilities and Corporate Access (CA) services need to be expanded. From this perspective, the U.S. boutique and middle market investment bank model—which integrates CA services and corporate finance on the foundation of industry-specialized research—offers significant implications. Domestic small- and mid-sized securities firms likewise need to build differentiated positioning grounded in industry expertise and to develop research into a strategic core asset that extends into the investment banking division. However, given that such objectives are difficult to achieve through industry efforts alone, complementary policy measures must be pursued in parallel, including policy support such as easing entry regulations and strengthening the SME-specialized securities firm designation scheme.
The Financial Services Commission, in December 2025, presented a structural reform agenda for the KOSDAQ market through the "KOSDAQ Market Trust + Innovation Enhancement Plan." The plan encompasses key initiatives including the strengthening of KOSDAQ's organizational independence and autonomy, the redesign of listing review and delisting frameworks, the improvement of conditions for institutional investor participation, and the enhancement of investor protection. It is expected to directly contribute to restoring confidence in the KOSDAQ market and improving the investment environment. In particular, the refinement of listing and delisting standards based on a high-entry/high-exit model, along with the expansion of the institutional investor base, is anticipated to facilitate the proactive identification of innovative companies and the timely delisting of underperforming ones, thereby restructuring the KOSDAQ market around high-growth innovative enterprises and broadening the foundation for long-term investment.
However, given the distinctive characteristics of listed companies and the nature of structural change, the current round of regulatory reforms alone is unlikely to be sufficient to achieve adequate monitoring of KOSDAQ-listed companies or a qualitative improvement in the market grounded in long-term investment. In recent years, the proportion of growth-stage companies listed on KOSDAQ under the technology exception listing track—companies whose value is driven by technological capability and R&D investment rather than financial performance—has been expanding. This makes it increasingly difficult to assess corporate value based solely on conventional financial metrics, and qualitative judgment regarding technological competitiveness and growth potential is becoming ever more critical. Accordingly, information that enables a comprehensive understanding of a company's business model, technological competitiveness, and positioning within its industry is becoming an essential basis for investment decisions. Furthermore, early-stage growth companies are inherently limited in their ability to generate near-term results, necessitating a stable investor base capable of evaluating and investing in such companies from a long-term perspective. Therefore, in order to advance the development of the KOSDAQ market, regulatory reform must be complemented by enhancements to the market's intermediation function—specifically, through the activation of information production on KOSDAQ-listed companies and the strengthening of linkages with institutional investors to foster long-term investment.
Securities firms serve as the key intermediaries through which these market functions are realized in practice, and in particular, their research capabilities and investor networks can act as critical enabling factors. In this regard, the role of securities firms needs to extend beyond simple issuance and brokerage functions to encompass the broader roles of information producer and connector between investors and listed companies. Domestic small- and mid-sized securities firms, however, have demonstrated deficiencies in both capacities. On the information production side, research operations are concentrated on large-cap stocks, resulting in limited analyst coverage of small- and mid-cap KOSDAQ companies. In terms of revenue structure, the relatively low weight of the investment banking segment has prevented small- and mid-cap research from being leveraged as a core information production infrastructure. Moreover, services that connect listed companies with institutional investors are largely absent. In this context, the U.S. experience—where research-driven small- and mid-cap investment banking has become an established business model—offers meaningful implications.
Case Studies of U.S. Small- and Mid-Sized Investment Banks
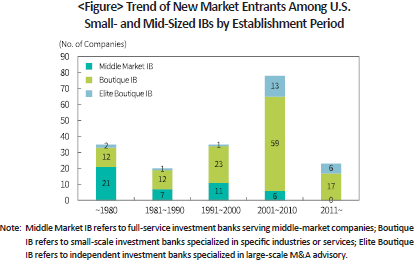
Unlike global investment banks (IBs) that focus on large-cap equities and large-scale transactions in the U.S. capital markets, middle market IBs and boutique IBs compete on the basis of business structures specialized in small- and mid-cap equities. In particular, the entry of new small- and mid-sized IBs began in earnest after the 1990s and expanded significantly throughout the 2000s, indicating that these firms have successfully established themselves not merely as a differentiation strategy, but as a viable business model that addresses the fundamental demand for reducing information asymmetry in the small- and mid-cap market and supporting capital raising, while simultaneously securing stable profitability. From a regulatory perspective, this expansion of new market entrants appears to be attributable to low capital requirements, an accessible registration regime, and an operating environment that has enabled capital-light business models.
The key distinguishing feature of U.S. small- and mid-sized investment banks (IBs) lies in their cultivation of specialized expertise through in-depth research focused on specific industries and small- to mid-cap equities. Particularly noteworthy is the fact that such industry expertise serves as a shared asset across all business lines, including institutional sales, investor connectivity, corporate finance advisory, and equity capital markets (ECM). This characteristic is observed not only in wholesale-oriented boutique IBs, but also at firms such as Raymond James and Stifel, which operate integrated business models combining both retail and wholesale functions offering meaningful implications for our domestic securities firms.
Raymond James maintains a top-tier position in small- and mid-cap coverage, providing research across ten core sectors. A defining feature of its research framework is its ability to analyze entire industries—rather than individual companies in isolation—through comprehensive coverage spanning entire supply chains, thereby enabling investors to make investment decisions within a broader industry context. Stifel, meanwhile, has established its competitive edge through qualitative differentiation rather than a simple expansion of research volume. Specifically, the firm delivers differentiated insights in innovation-driven growth sectors where information asymmetry is pronounced, through primary-source analysis drawing on proprietary events, management and corporate site visits, distribution channel checks, surveys of clients and key opinion leaders (KOLs), and networks of industry experts.
Research strategies specialized in growth industries are also observed among small-scale boutique investment banks focused on ECM services. Lake Street Capital Markets selects small- and mid-cap innovative companies that align with long-term growth themes and provides institutional investors with in-depth information. LifeSci Capital, specialized in life sciences, secures primary industry intelligence through physician surveys, conference coverage, and expert networks, combining this with active investor engagement to deliver differentiated services. The firm also distributes independent research broadly to institutional investor groups, expanding touchpoints with investors—demonstrating that the role of research is extending beyond information production toward the formation of market networks.
On the other hand, U.S. small- and mid-sized investment banks generally operate Corporate Access (CA) services that connect companies with investors, underpinned by small- and mid-cap equity research. Piper Sandler, leveraging its position as the second-ranked firm in U.S. small- and mid-cap research coverage, provides extensive CA services, hosting more than 30,000 conferences, events, non-deal roadshows (NDRs), and one-on-one meetings annually. The firm also ranks first on a buy-side basis in small- and mid-cap liquidity provision, which underscores that research functions as a critical piece of infrastructure closely linked not only to expanding the investor base but also to facilitating liquidity formation in the market. Leerink Partners, a firm specialized in healthcare, similarly leverages its healthcare sector research and industry practitioner networks to conduct more than 7,500 roadshows, NDRs, one-on-one meetings, and conferences annually, broadening the interface between investors and companies.
These examples illustrate that U.S. small- and mid-sized investment banks generally fulfill core capital markets functions in the small- and mid-cap segment—namely, information production, investor base formation, market liquidity provision, and ultimately capital raising—through in-depth research and CA services. From a business strategy perspective, deep research concentrated on specific industries and small- and mid-cap equities cultivates differentiated sector-specific analytical capabilities while simultaneously serving as content that supports CA activities; CA activities, in turn, expand access to corporate management, thereby enhancing the depth of research analysis. Furthermore, these two services connect to corporate finance competitiveness—encompassing IPOs, follow-on offerings, and M&A advisory—through improvements in deal origination, valuation capabilities, and institutional investor networks. The fact that the research and investment banking divisions of U.S. small- and mid-cap firms share the same industry verticals as their areas of specialization plainly demonstrates the advantages of this integrated structure. Within this framework, research functions as a core asset underpinning the overall competitiveness of the business, even where its standalone profitability may be limited.
Implications
Directly applying the U.S. small- and mid-sized IB business model to Korea’s capital market faces several structural constraints. Compared to the United States, Korea's institutional investor base is shallower, with only a limited number of asset managers specializing in small- and mid-cap growth companies. Small research teams and a large-cap-oriented coverage structure at small- and mid-sized securities firms further hinder the accumulation of deep sector-specific expertise. Unlike in the United States, CA activities targeting small- and mid-cap companies have yet to gain traction in the domestic capital markets. Nevertheless, the U.S. experience offers strategic implications for smaller securities firms in the context of developing the KOSDAQ market. First, small- and mid-sized securities firms need to accumulate sector expertise through research specialized in specific industries and, on that basis, establish a differentiated positioning. This approach is not merely a pragmatic response to resource constraints, but a necessary condition for building a competitive advantage rooted in specialization. In particular, as market assessments of KOSDAQ-listed companies increasingly center on technological capabilities and growth potential, strengthening information-production capacity through in-depth research and achieving differentiation are of critical importance. Second, research must be repositioned beyond a mere information-production function to serve as a core asset underpinning the firm's overall competitiveness across CA, corporate finance, and other business lines. As evidenced by the U.S. experience, CA serves both as a means of extending the research function and as a service that, in its own right, delivers value to both companies and institutional investors. In this regard, domestic small- and mid-sized securities firms also need to actively expand CA services linked to their research capabilities, which can directly contribute to the appropriate valuation of KOSDAQ-listed companies and to broadening institutional investor participation.
Since these structural constraints cannot be resolved by small- and mid-sized securities firms alone, complementary policy support is needed to facilitate the transition to this business model. One feasible starting point would be to introduce targeted support and incentives for developing sector-specialized research and CA capabilities, for example, by easing entry regulations and strengthening the SME-specialized securities firm designation scheme.
However, given the distinctive characteristics of listed companies and the nature of structural change, the current round of regulatory reforms alone is unlikely to be sufficient to achieve adequate monitoring of KOSDAQ-listed companies or a qualitative improvement in the market grounded in long-term investment. In recent years, the proportion of growth-stage companies listed on KOSDAQ under the technology exception listing track—companies whose value is driven by technological capability and R&D investment rather than financial performance—has been expanding. This makes it increasingly difficult to assess corporate value based solely on conventional financial metrics, and qualitative judgment regarding technological competitiveness and growth potential is becoming ever more critical. Accordingly, information that enables a comprehensive understanding of a company's business model, technological competitiveness, and positioning within its industry is becoming an essential basis for investment decisions. Furthermore, early-stage growth companies are inherently limited in their ability to generate near-term results, necessitating a stable investor base capable of evaluating and investing in such companies from a long-term perspective. Therefore, in order to advance the development of the KOSDAQ market, regulatory reform must be complemented by enhancements to the market's intermediation function—specifically, through the activation of information production on KOSDAQ-listed companies and the strengthening of linkages with institutional investors to foster long-term investment.
Securities firms serve as the key intermediaries through which these market functions are realized in practice, and in particular, their research capabilities and investor networks can act as critical enabling factors. In this regard, the role of securities firms needs to extend beyond simple issuance and brokerage functions to encompass the broader roles of information producer and connector between investors and listed companies. Domestic small- and mid-sized securities firms, however, have demonstrated deficiencies in both capacities. On the information production side, research operations are concentrated on large-cap stocks, resulting in limited analyst coverage of small- and mid-cap KOSDAQ companies. In terms of revenue structure, the relatively low weight of the investment banking segment has prevented small- and mid-cap research from being leveraged as a core information production infrastructure. Moreover, services that connect listed companies with institutional investors are largely absent. In this context, the U.S. experience—where research-driven small- and mid-cap investment banking has become an established business model—offers meaningful implications.
Case Studies of U.S. Small- and Mid-Sized Investment Banks
Unlike global investment banks (IBs) that focus on large-cap equities and large-scale transactions in the U.S. capital markets, middle market IBs and boutique IBs compete on the basis of business structures specialized in small- and mid-cap equities. In particular, the entry of new small- and mid-sized IBs began in earnest after the 1990s and expanded significantly throughout the 2000s, indicating that these firms have successfully established themselves not merely as a differentiation strategy, but as a viable business model that addresses the fundamental demand for reducing information asymmetry in the small- and mid-cap market and supporting capital raising, while simultaneously securing stable profitability. From a regulatory perspective, this expansion of new market entrants appears to be attributable to low capital requirements, an accessible registration regime, and an operating environment that has enabled capital-light business models.
The key distinguishing feature of U.S. small- and mid-sized investment banks (IBs) lies in their cultivation of specialized expertise through in-depth research focused on specific industries and small- to mid-cap equities. Particularly noteworthy is the fact that such industry expertise serves as a shared asset across all business lines, including institutional sales, investor connectivity, corporate finance advisory, and equity capital markets (ECM). This characteristic is observed not only in wholesale-oriented boutique IBs, but also at firms such as Raymond James and Stifel, which operate integrated business models combining both retail and wholesale functions offering meaningful implications for our domestic securities firms.
Raymond James maintains a top-tier position in small- and mid-cap coverage, providing research across ten core sectors. A defining feature of its research framework is its ability to analyze entire industries—rather than individual companies in isolation—through comprehensive coverage spanning entire supply chains, thereby enabling investors to make investment decisions within a broader industry context. Stifel, meanwhile, has established its competitive edge through qualitative differentiation rather than a simple expansion of research volume. Specifically, the firm delivers differentiated insights in innovation-driven growth sectors where information asymmetry is pronounced, through primary-source analysis drawing on proprietary events, management and corporate site visits, distribution channel checks, surveys of clients and key opinion leaders (KOLs), and networks of industry experts.
Research strategies specialized in growth industries are also observed among small-scale boutique investment banks focused on ECM services. Lake Street Capital Markets selects small- and mid-cap innovative companies that align with long-term growth themes and provides institutional investors with in-depth information. LifeSci Capital, specialized in life sciences, secures primary industry intelligence through physician surveys, conference coverage, and expert networks, combining this with active investor engagement to deliver differentiated services. The firm also distributes independent research broadly to institutional investor groups, expanding touchpoints with investors—demonstrating that the role of research is extending beyond information production toward the formation of market networks.
On the other hand, U.S. small- and mid-sized investment banks generally operate Corporate Access (CA) services that connect companies with investors, underpinned by small- and mid-cap equity research. Piper Sandler, leveraging its position as the second-ranked firm in U.S. small- and mid-cap research coverage, provides extensive CA services, hosting more than 30,000 conferences, events, non-deal roadshows (NDRs), and one-on-one meetings annually. The firm also ranks first on a buy-side basis in small- and mid-cap liquidity provision, which underscores that research functions as a critical piece of infrastructure closely linked not only to expanding the investor base but also to facilitating liquidity formation in the market. Leerink Partners, a firm specialized in healthcare, similarly leverages its healthcare sector research and industry practitioner networks to conduct more than 7,500 roadshows, NDRs, one-on-one meetings, and conferences annually, broadening the interface between investors and companies.
These examples illustrate that U.S. small- and mid-sized investment banks generally fulfill core capital markets functions in the small- and mid-cap segment—namely, information production, investor base formation, market liquidity provision, and ultimately capital raising—through in-depth research and CA services. From a business strategy perspective, deep research concentrated on specific industries and small- and mid-cap equities cultivates differentiated sector-specific analytical capabilities while simultaneously serving as content that supports CA activities; CA activities, in turn, expand access to corporate management, thereby enhancing the depth of research analysis. Furthermore, these two services connect to corporate finance competitiveness—encompassing IPOs, follow-on offerings, and M&A advisory—through improvements in deal origination, valuation capabilities, and institutional investor networks. The fact that the research and investment banking divisions of U.S. small- and mid-cap firms share the same industry verticals as their areas of specialization plainly demonstrates the advantages of this integrated structure. Within this framework, research functions as a core asset underpinning the overall competitiveness of the business, even where its standalone profitability may be limited.
Implications
Directly applying the U.S. small- and mid-sized IB business model to Korea’s capital market faces several structural constraints. Compared to the United States, Korea's institutional investor base is shallower, with only a limited number of asset managers specializing in small- and mid-cap growth companies. Small research teams and a large-cap-oriented coverage structure at small- and mid-sized securities firms further hinder the accumulation of deep sector-specific expertise. Unlike in the United States, CA activities targeting small- and mid-cap companies have yet to gain traction in the domestic capital markets. Nevertheless, the U.S. experience offers strategic implications for smaller securities firms in the context of developing the KOSDAQ market. First, small- and mid-sized securities firms need to accumulate sector expertise through research specialized in specific industries and, on that basis, establish a differentiated positioning. This approach is not merely a pragmatic response to resource constraints, but a necessary condition for building a competitive advantage rooted in specialization. In particular, as market assessments of KOSDAQ-listed companies increasingly center on technological capabilities and growth potential, strengthening information-production capacity through in-depth research and achieving differentiation are of critical importance. Second, research must be repositioned beyond a mere information-production function to serve as a core asset underpinning the firm's overall competitiveness across CA, corporate finance, and other business lines. As evidenced by the U.S. experience, CA serves both as a means of extending the research function and as a service that, in its own right, delivers value to both companies and institutional investors. In this regard, domestic small- and mid-sized securities firms also need to actively expand CA services linked to their research capabilities, which can directly contribute to the appropriate valuation of KOSDAQ-listed companies and to broadening institutional investor participation.
Since these structural constraints cannot be resolved by small- and mid-sized securities firms alone, complementary policy support is needed to facilitate the transition to this business model. One feasible starting point would be to introduce targeted support and incentives for developing sector-specialized research and CA capabilities, for example, by easing entry regulations and strengthening the SME-specialized securities firm designation scheme.